Your Neighbour's Smith Manoeuvre™ Was Built on 20 Years of Equity You Don't Have
Hearing how someone further along invests through their mortgage can make your own steady payment and modest savings balance look timid overnight. The usual advice is to learn from people who are ahead of you, and much of the time that advice is good. What it skips is the step where you check what they're standing on before you copy what they're doing. Feeling behind is a poor reason to choose your next debt.
Maybe you've looked at your mortgage balance after hearing how a neighbour borrows against their home to invest, and wondered whether ordinary saving means you're falling behind. That comparison deserves a hard look. A strategy is not a shortcut if it requires financial resilience you haven't built yet. Before you take on more debt, the real question is whether your household could keep paying everything it owes if markets dropped or a paycheque stopped. Whether the strategy can work at all is a separate, smaller question.
Why the same strategy can put your household at greater risk
The Smith Manoeuvre™ usually runs through a readvanceable mortgage. As you pay down principal, the credit line attached to the mortgage grows by the same amount, and that room is borrowed to buy eligible income-producing investments. Under CRA rules, interest can be deductible when borrowed money is used to earn income from a business or property. Securing the loan against your home doesn't make the interest deductible. How you use the money does.
Lenders generally want at least 20% equity before a readvanceable mortgage is even available. Clearing that bar is only the starting point. Once you're borrowing to invest, a falling market shrinks the investments while the loan stays exactly the same size. The interest bill keeps arriving every month whether your portfolio is up or down.
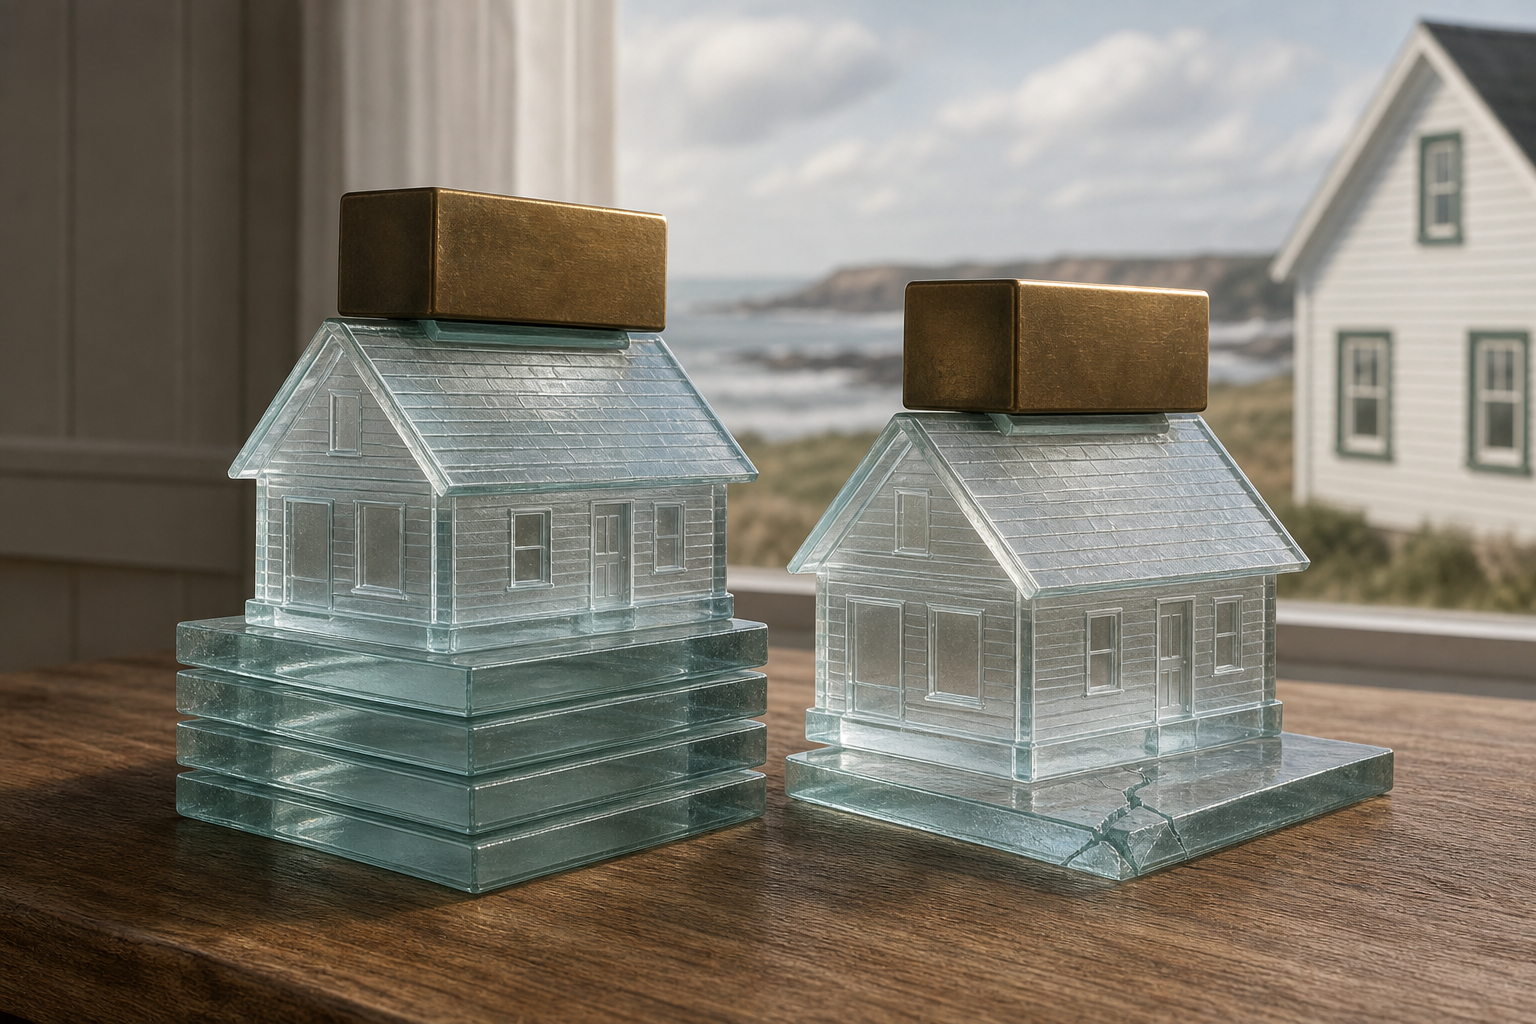
A household with two decades of equity, dependable income and solid cash reserves can ride out a bad stretch without touching its investments. A young family three years into ownership, just past 20% equity and running on one income, may have to sell at the worst possible moment to keep up with payments. The two households can use the identical strategy and carry very different levels of risk.
What to copy from an advanced plan before you take on the debt
Your neighbour's plan still holds lessons you can use right away: pay attention to tax, invest for the long term, and treat your mortgage and investments as one connected plan. None of those requires borrowing.
Before any leverage, run your household through a bad period on paper:
What supports the borrowing? Available equity, reliable cash flow and savings you can reach quickly matter far more than how sophisticated the plan sounds.
Could you get through six lean months? Picture covering the mortgage, the investment-loan interest, groceries and utilities through an income gap without selling investments at a loss.
Are you treating the tax angle as a safety net? A possible deduction lowers the cost of the debt. It doesn't remove the debt, and it does nothing to protect the investment.
Your next move depends on where you actually stand. If you're an eligible first-time buyer still saving, a First Home Savings Account may fit better. Eligible contributions are generally deductible and qualifying withdrawals are tax-free, with limits of $8,000 a year and $40,000 over your lifetime, subject to available room. If you already own, the better step may be building a deeper cash reserve or clearing high-interest credit card debt.
The right time for leverage comes when your household can absorb a bad year, whatever your age and whatever your neighbour is doing.
A simpler plan, chosen on purpose, keeps you investing through setbacks instead of forcing you out of the market when you can least afford it. Before you pursue the Smith Manoeuvre™ or any other mortgage-based investing, ask one question at your kitchen table: could we carry this borrowing through an income interruption without being forced to sell? If the answer isn't clearly yes, that's worth working through with someone who can look at your mortgage, your investments and your taxes together.


Hearing how someone further along invests through their mortgage can make your own steady payment and modest savings balance look timid overnight. The usual advice is to learn from people who are ahead of you, and much of the time that advice is good. What it skips is the step where you check what they're standing on before you copy what they're doing. Feeling behind is a poor reason to choose your next debt.
Maybe you've looked at your mortgage balance after hearing how a neighbour borrows against their home to invest, and wondered whether ordinary saving means you're falling behind. That comparison deserves a hard look. A strategy is not a shortcut if it requires financial resilience you haven't built yet. Before you take on more debt, the real question is whether your household could keep paying everything it owes if markets dropped or a paycheque stopped. Whether the strategy can work at all is a separate, smaller question.
Why the same strategy can put your household at greater risk
The Smith Manoeuvre™ usually runs through a readvanceable mortgage. As you pay down principal, the credit line attached to the mortgage grows by the same amount, and that room is borrowed to buy eligible income-producing investments. Under CRA rules, interest can be deductible when borrowed money is used to earn income from a business or property. Securing the loan against your home doesn't make the interest deductible. How you use the money does.
Lenders generally want at least 20% equity before a readvanceable mortgage is even available. Clearing that bar is only the starting point. Once you're borrowing to invest, a falling market shrinks the investments while the loan stays exactly the same size. The interest bill keeps arriving every month whether your portfolio is up or down.
A household with two decades of equity, dependable income and solid cash reserves can ride out a bad stretch without touching its investments. A young family three years into ownership, just past 20% equity and running on one income, may have to sell at the worst possible moment to keep up with payments. The two households can use the identical strategy and carry very different levels of risk.
What to copy from an advanced plan before you take on the debt
Your neighbour's plan still holds lessons you can use right away: pay attention to tax, invest for the long term, and treat your mortgage and investments as one connected plan. None of those requires borrowing.
Before any leverage, run your household through a bad period on paper:
Your next move depends on where you actually stand. If you're an eligible first-time buyer still saving, a First Home Savings Account may fit better. Eligible contributions are generally deductible and qualifying withdrawals are tax-free, with limits of $8,000 a year and $40,000 over your lifetime, subject to available room. If you already own, the better step may be building a deeper cash reserve or clearing high-interest credit card debt.
The right time for leverage comes when your household can absorb a bad year, whatever your age and whatever your neighbour is doing.
A simpler plan, chosen on purpose, keeps you investing through setbacks instead of forcing you out of the market when you can least afford it. Before you pursue the Smith Manoeuvre™ or any other mortgage-based investing, ask one question at your kitchen table: could we carry this borrowing through an income interruption without being forced to sell? If the answer isn't clearly yes, that's worth working through with someone who can look at your mortgage, your investments and your taxes together.
Read Next
Lump-Sum Inheritance or a Testamentary Trust? Here's Who Each One Is For
A $2,000 Storm Bill Is the Liquidity Test Most Canadians Are Failing
Capital Gains Are the Wrong Scoreboard When Your Income Can Vanish
Your Paid-Off House Can't Pay the Grocery Bill in Retirement