Lump-Sum Inheritance or a Testamentary Trust? Here's Who Each One Is For
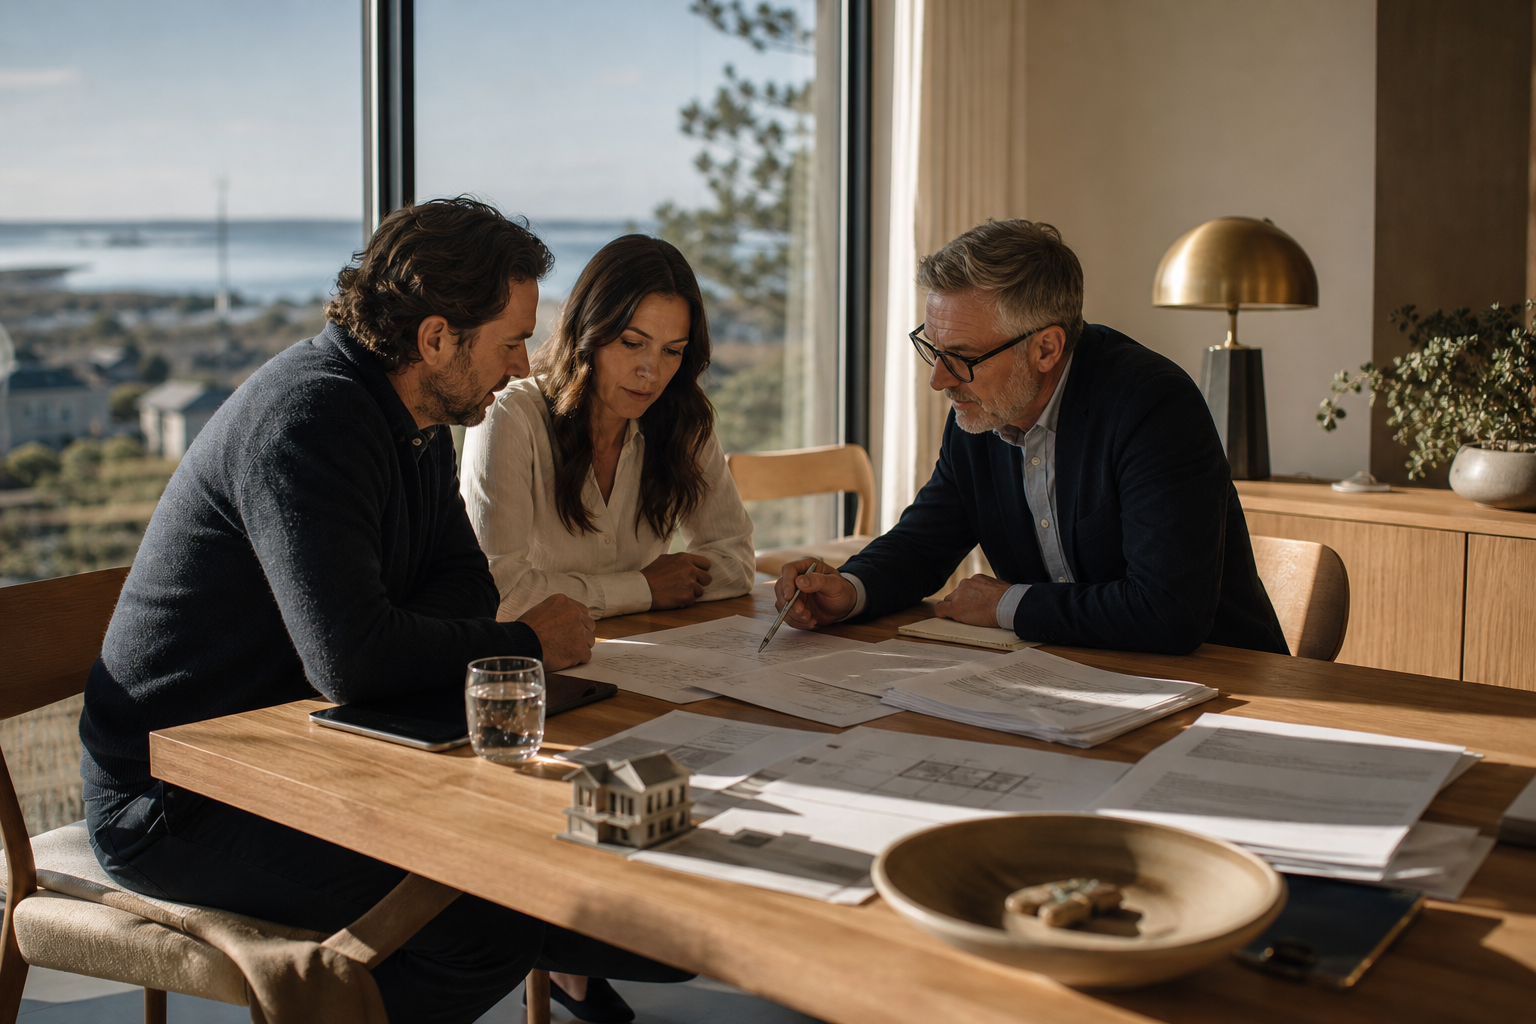
You want your life's work to support your kids, not derail them. When you plan how to leave that money behind, you're usually looking at two choices: an outright lump-sum payout, or a structured testamentary trust written into your will.
Both work. They work for different families because they trade off completely different risks.
Option one: the outright lump sum
What it gives you: clean closure. The money transfers directly to your adult children, the estate closes, and no one is stuck running paperwork for the next decade. It shows trust and avoids ongoing administrative friction.
What it costs: protection. Handing over an unmanaged lump sum leaves the money exposed to divorce claims, business creditors, and sudden lifestyle inflation.
Where it bites: when life goes sideways. If a child goes through a marriage breakdown, faces a lawsuit, or simply isn't ready to handle a sudden windfall, the inheritance can vanish quickly.
Option two: the structured testamentary trust
What it gives you: a legal shield and behavioral guardrails. The capital stays protected from outside claims and creditors, and you can prevent a child from spending through their entire inheritance in a few short years.
What it costs: real money and ongoing friction. A trust requires annual tax filings, accounting carry costs, and legal oversight. Over time, those professional fees can burn up tens of thousands of dollars.
Where it bites: over-engineering out of anxiety. If the estate isn't large enough to justify the annual carry costs, fees eat up the capital. Worse, if you name one child to manage money for another, you risk fracturing family relationships.
Who each one is for
An outright lump sum fits if your children are financially grounded, their personal and professional lives carry little legal exposure, and the estate is small enough that ongoing accounting bills would take too big a bite.
A structured testamentary trust fits if your beneficiaries face real exposure to divorce or creditors, or if the size of the estate warrants paying annual professional fees to prevent rapid lifestyle inflation.
How to find the middle ground
Protecting an inheritance isn't about controlling your adult kids from the grave. It's about weighing the real friction of a trust against the real risks of a lump sum. If you want a practical way to balance both, consider what's known as the Balanced Bequest Blueprint:
Audit your beneficiaries for real legal and financial exposure instead of general worry.
Run the annual accounting and legal carry costs of a testamentary trust against your actual estate size to see if the structure pays for itself.
Stage capital distributions across milestone ages rather than picking an all-or-nothing payout.
Name a professional or neutral co-trustee so siblings never have to police each other's money.


You want your life's work to support your kids, not derail them. When you plan how to leave that money behind, you're usually looking at two choices: an outright lump-sum payout, or a structured testamentary trust written into your will.
Both work. They work for different families because they trade off completely different risks.
Option one: the outright lump sum
What it gives you: clean closure. The money transfers directly to your adult children, the estate closes, and no one is stuck running paperwork for the next decade. It shows trust and avoids ongoing administrative friction.
What it costs: protection. Handing over an unmanaged lump sum leaves the money exposed to divorce claims, business creditors, and sudden lifestyle inflation.
Where it bites: when life goes sideways. If a child goes through a marriage breakdown, faces a lawsuit, or simply isn't ready to handle a sudden windfall, the inheritance can vanish quickly.
Option two: the structured testamentary trust
What it gives you: a legal shield and behavioral guardrails. The capital stays protected from outside claims and creditors, and you can prevent a child from spending through their entire inheritance in a few short years.
What it costs: real money and ongoing friction. A trust requires annual tax filings, accounting carry costs, and legal oversight. Over time, those professional fees can burn up tens of thousands of dollars.
Where it bites: over-engineering out of anxiety. If the estate isn't large enough to justify the annual carry costs, fees eat up the capital. Worse, if you name one child to manage money for another, you risk fracturing family relationships.
Who each one is for
An outright lump sum fits if your children are financially grounded, their personal and professional lives carry little legal exposure, and the estate is small enough that ongoing accounting bills would take too big a bite.
A structured testamentary trust fits if your beneficiaries face real exposure to divorce or creditors, or if the size of the estate warrants paying annual professional fees to prevent rapid lifestyle inflation.
How to find the middle ground
Protecting an inheritance isn't about controlling your adult kids from the grave. It's about weighing the real friction of a trust against the real risks of a lump sum. If you want a practical way to balance both, consider what's known as the Balanced Bequest Blueprint:
Read Next
A $2,000 Storm Bill Is the Liquidity Test Most Canadians Are Failing
Capital Gains Are the Wrong Scoreboard When Your Income Can Vanish
Your Paid-Off House Can't Pay the Grocery Bill in Retirement
If Your Slow Months Need a Credit Card, Your Good Months Aren't Good Enough