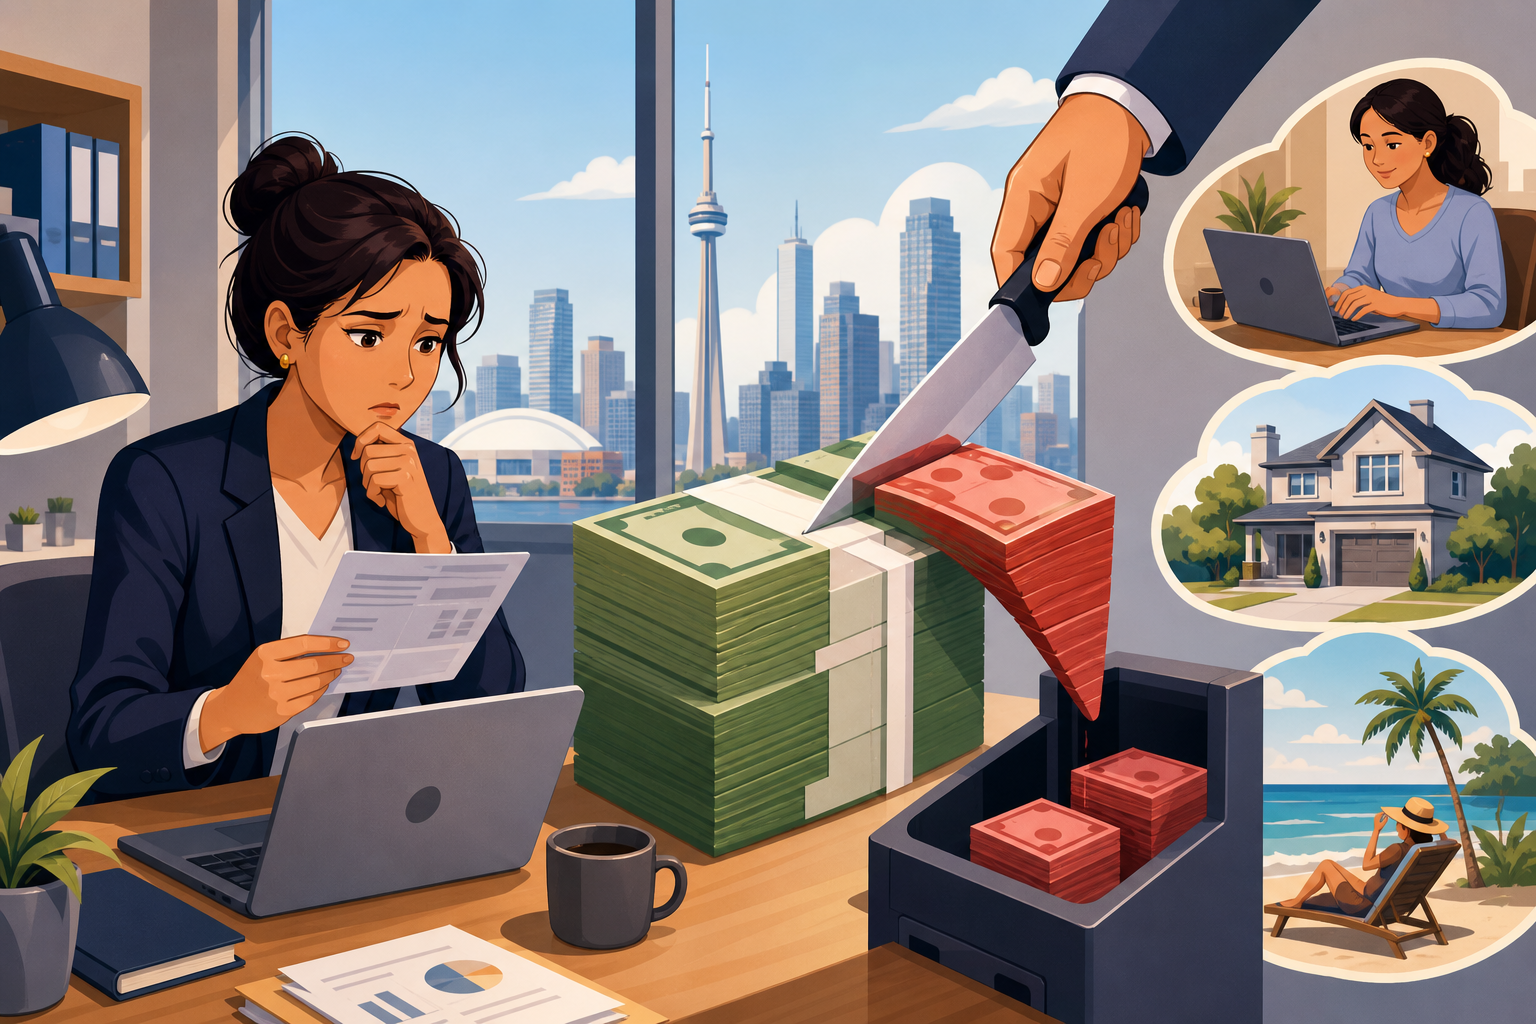
Budget your next raise, bonus or contract on what lands in your account after tax, worked out at the rate that applies to those extra dollars. For Ontario high earners, that figure is usually lower than last year's average tax rate would suggest, and the gap is where plans go sideways.
The Rate That Actually Governs Decisions
Your average tax rate is your total tax divided by your total income. Your marginal rate is what applies to your next dollar. When you're deciding whether to take on a consulting contract, start a side business, or refinance your home to invest, the marginal rate tells you what the extra income is worth. The average rate from last year's return will flatter it.
Here's simple, hypothetical arithmetic. Say the entire additional $10,000 is taxed at an assumed 43.4% income-tax rate. Tax is $4,340. Take-home is $5,660, before CPP, EI or any other payroll deductions. You keep 56.6 cents of each extra dollar. The 43.4% is an illustration chosen to make the math easy to follow, and it should not be read as a confirmed 2026 Ontario bracket. Your own rate comes from the current federal and Ontario rate tables applied to your projected taxable income.
Three Things People Get Wrong About Brackets
Calculate new income slice by slice when it spans brackets. If part of a $10,000 bonus falls below a bracket threshold and part falls above it, each portion gets its own rate. Using the hypothetical rates above, $4,000 taxed at an assumed 40% and $6,000 at an assumed 43.4% produces $1,600 plus $2,604, or $4,204 in tax, leaving $5,796.
Stop worrying that a raise will shrink your total pay. Crossing into a higher bracket changes the rate only on the dollars above the threshold. Every dollar below it is taxed exactly as it was before the raise.
Treat your pay stub as an estimate. Payroll withholding is calculated per pay period from your TD1 forms, and bonuses are often withheld using a different method than regular salary. Your final liability gets settled on your return. A big withholding on a bonus cheque can come back as a refund, and a side contract with no withholding at all can turn into a balance owing in April.
Where This Shows Up In Real Decisions
Consider a business owner with an incorporated practice who has an extra $40,000 of profit this year and doesn't need the cash personally. Leaving it in the corporation as retained earnings means it's taxed at corporate rates for now, which for active business income are generally lower than top personal rates. The personal tax hasn't disappeared. It arrives when the money comes out as salary or dividends, possibly in a year when the owner's personal income is lower, possibly not.
So retained earnings are a deferral tool. Whether they produce a lasting saving depends on how long the money stays inside, what it earns there, future personal and corporate rates, and how it's eventually paid out. Dividends are not automatically cheaper than salary either: salary creates RRSP contribution room and CPP credits that dividends don't, and the dividend tax credit is designed to roughly even out the two over time. Add the accounting, legal and annual filing costs of a corporation and the answer is specific to each owner's numbers.
Interest deductions work on a similar principle. Interest on money borrowed and used directly for an eligible income-earning purpose, such as buying non-registered investments with a reasonable expectation of income, may be deductible. The use of the borrowed funds is what counts, and you need to be able to trace it. Money borrowed for a TFSA, an RRSP, a vacation or your own home generally doesn't qualify, and mixing borrowed and personal money in one account makes the trail hard to defend.
When the deduction is allowed, it reduces taxable income. It isn't a guaranteed refund cheque. In a purely hypothetical case, if $5,000 of interest were fully deductible and the taxpayer's marginal rate on that income were an assumed 40%, the deduction would reduce tax by $2,000, for an after-tax interest cost of $3,000. At a lower marginal rate, the same interest costs more after tax.
This is the math behind the Smith Manoeuvre™, which gradually converts non-deductible mortgage debt into investment borrowing by re-borrowing paid-down principal and investing it. Any tax benefit depends on eligible use, clean documentation, your marginal rate, and your circumstances each year. The investments can also fall in value while the borrowed money is still owed, so the strategy carries real risk alongside any potential deduction.
How To Find Your Rate And Use It
Pull last year's tax return. Find your total taxable income on line 26000. That's your starting point, not your answer.
Project this year's taxable income. Add salary, bonus, side income, rental income and business profit, then subtract deductions you expect to claim, such as RRSP contributions and eligible carrying charges.
Look up the current federal and Ontario rate tables. Use the rates published by the CRA and the Ontario government for the year in question. Online tax calculators are handy for a quick estimate, but they aren't official verification.
Split your new income by bracket. Apply each rate to its own slice and add the results. That total, subtracted from the new income, is what you can budget.
Compare withholding to your projected bill. If you have untaxed side or rental income, set cash aside every month or update your TD1 so April doesn't surprise you.
Model both paths if you're incorporated. Compare retaining income in the corporation with paying it out, and include the personal tax you'll owe when it eventually comes out.
Document borrowed money before you invest it. Keep investment borrowing in a separate account, record where each dollar went, and confirm eligibility before counting on any deduction.
Before year-end, sit down with a projected income and expense review that shows what each new dollar is likely to net you after tax. Then get advice from a qualified tax professional before you incorporate, refinance to invest, or start the Smith Manoeuvre™, so your mortgage, investment and tax decisions are built from the same set of numbers.


Budget your next raise, bonus or contract on what lands in your account after tax, worked out at the rate that applies to those extra dollars. For Ontario high earners, that figure is usually lower than last year's average tax rate would suggest, and the gap is where plans go sideways.
The Rate That Actually Governs Decisions
Your average tax rate is your total tax divided by your total income. Your marginal rate is what applies to your next dollar. When you're deciding whether to take on a consulting contract, start a side business, or refinance your home to invest, the marginal rate tells you what the extra income is worth. The average rate from last year's return will flatter it.
Here's simple, hypothetical arithmetic. Say the entire additional $10,000 is taxed at an assumed 43.4% income-tax rate. Tax is $4,340. Take-home is $5,660, before CPP, EI or any other payroll deductions. You keep 56.6 cents of each extra dollar. The 43.4% is an illustration chosen to make the math easy to follow, and it should not be read as a confirmed 2026 Ontario bracket. Your own rate comes from the current federal and Ontario rate tables applied to your projected taxable income.
Three Things People Get Wrong About Brackets
Where This Shows Up In Real Decisions
Consider a business owner with an incorporated practice who has an extra $40,000 of profit this year and doesn't need the cash personally. Leaving it in the corporation as retained earnings means it's taxed at corporate rates for now, which for active business income are generally lower than top personal rates. The personal tax hasn't disappeared. It arrives when the money comes out as salary or dividends, possibly in a year when the owner's personal income is lower, possibly not.
So retained earnings are a deferral tool. Whether they produce a lasting saving depends on how long the money stays inside, what it earns there, future personal and corporate rates, and how it's eventually paid out. Dividends are not automatically cheaper than salary either: salary creates RRSP contribution room and CPP credits that dividends don't, and the dividend tax credit is designed to roughly even out the two over time. Add the accounting, legal and annual filing costs of a corporation and the answer is specific to each owner's numbers.
Interest deductions work on a similar principle. Interest on money borrowed and used directly for an eligible income-earning purpose, such as buying non-registered investments with a reasonable expectation of income, may be deductible. The use of the borrowed funds is what counts, and you need to be able to trace it. Money borrowed for a TFSA, an RRSP, a vacation or your own home generally doesn't qualify, and mixing borrowed and personal money in one account makes the trail hard to defend.
When the deduction is allowed, it reduces taxable income. It isn't a guaranteed refund cheque. In a purely hypothetical case, if $5,000 of interest were fully deductible and the taxpayer's marginal rate on that income were an assumed 40%, the deduction would reduce tax by $2,000, for an after-tax interest cost of $3,000. At a lower marginal rate, the same interest costs more after tax.
This is the math behind the Smith Manoeuvre™, which gradually converts non-deductible mortgage debt into investment borrowing by re-borrowing paid-down principal and investing it. Any tax benefit depends on eligible use, clean documentation, your marginal rate, and your circumstances each year. The investments can also fall in value while the borrowed money is still owed, so the strategy carries real risk alongside any potential deduction.
How To Find Your Rate And Use It
Before year-end, sit down with a projected income and expense review that shows what each new dollar is likely to net you after tax. Then get advice from a qualified tax professional before you incorporate, refinance to invest, or start the Smith Manoeuvre™, so your mortgage, investment and tax decisions are built from the same set of numbers.
Read Next
Lump-Sum Inheritance or a Testamentary Trust? Here's Who Each One Is For
A $2,000 Storm Bill Is the Liquidity Test Most Canadians Are Failing
Capital Gains Are the Wrong Scoreboard When Your Income Can Vanish
Your Paid-Off House Can't Pay the Grocery Bill in Retirement