Your $500K Budget Buys a Condo in Toronto or a Four-Bedroom in Kelowna, Why Most Buyers Miss This When They Shop
A studio condo in downtown Toronto came with 480 square feet, $650 monthly maintenance, and a parking space that cost extra. The listing showed a Murphy bed and a counter-height table wedged against a window. That same week, a buyer in Kelowna closed on a four-bedroom detached home with a finished basement, a front yard, and a detached garage. Both properties sold for $500,000. The qualification paperwork looked almost identical.
The difference wasn't price. The difference was what the price bought. One buyer got density. The other got square footage. Most shopping begins with a budget number and ends with whatever fits inside that number. That sequence is backward.
The Leverage Shift Buyers Miss
In Toronto, $500,000 in September 2026 puts you at the bottom of the buyer hierarchy. You are shopping entry-level inventory in a market where the benchmark detached home is $993,410. Sellers know your budget before you walk through the door, and they know you don't have much room to move. Asking for repairs, negotiating on closing dates, or requesting a home inspection with contingencies puts you at the back of the line behind buyers with deeper pockets.
In Kelowna, that same $500,000 makes you the premium buyer. You can afford most of what's on the market, which means you dictate terms. Sellers accommodate your timeline. They fix the roof. They include the appliances. The transaction structure bends toward you because you're the one with the money, not the one barely scraping into the market. This isn't a personality difference. It's structural. The amount of capital you control relative to the local price distribution determines whether you negotiate or whether you take what you can get.
What the Same Number Actually Buys
In the Greater Toronto Area, a $500,000 budget typically secures a one-bedroom condo under 600 square feet, often in an aging building where monthly maintenance fees run $850 to $1,100. Those fees reduce your mortgage qualification by roughly $100,000 to $150,000 compared to a freehold property with no monthly fee load. The real carrying cost isn't the mortgage. It's the mortgage plus the fee plus the property tax, and that combination eats discretionary income faster than most first-time buyers anticipate.
In Alberta or Saskatchewan mid-sized cities, $500,000 buys a three-bedroom detached bungalow, sometimes four bedrooms if the property is listed between $485,000 and $515,000. The maintenance responsibility shifts to the homeowner, but there's no monthly fee bleeding the budget. Property taxes in these markets typically run 30 to 50 percent lower than comparable Toronto rates, and parking isn't a separate line item, it's a driveway attached to a house you own outright, land included.
The appreciation story differs too. Condos in high-density markets tend to appreciate when supply is constrained, but the land-to-building ratio works against you. A condo appreciates at the rate of scarcity and demand. A detached home with land appreciates at the rate of land value plus scarcity and demand. Over a decade, that spread compounds.
The Cost No One Factors In
Maintenance fees aren't mortgage payments, so they don't appear in the purchase price. But $900 per month at 5.25 percent over 25 years is equivalent to roughly $150,000 in borrowing power you're not using on the principal asset. A buyer who ignores this treats a $500,000 condo as equivalent to a $500,000 house. It isn't. The condo's true cost to carry resembles a $650,000 freehold mortgage when you add the fees back in.
This is where remorse starts. Two years in, the unit feels smaller. The fees go up. The building needs a special assessment. The equity gain is modest because twenty other identical units listed in the same complex, and now you're competing against yourself to sell. Meanwhile, the buyer in Kelowna has a basement they converted into a rental suite, which covers part of the mortgage.
Where This Leaves You
Some buyers don't have options. The job is in Vancouver. The aging parents are in Ottawa. The custody arrangement requires proximity to a specific school district. Geography binds you, and the strategy has to work within that constraint. Acknowledged.
For everyone else, the question isn't "What can I afford?" The question is "What does this $500,000 need to accomplish?" If the goal is space for a growing family, a home office, or a workshop, buying a condo in a high-cost market delays that goal by five to seven years while you wait for enough equity to trade up. If the goal is proximity to a specific industry, nightlife, or transit hub, the square footage concession might be worth it.
But most buyers don't ask that question. They ask "What's the nicest thing I can buy for $500,000?" and then they buy it without measuring it against the life they're actually trying to build. That's the gap. Not affordability. Alignment.



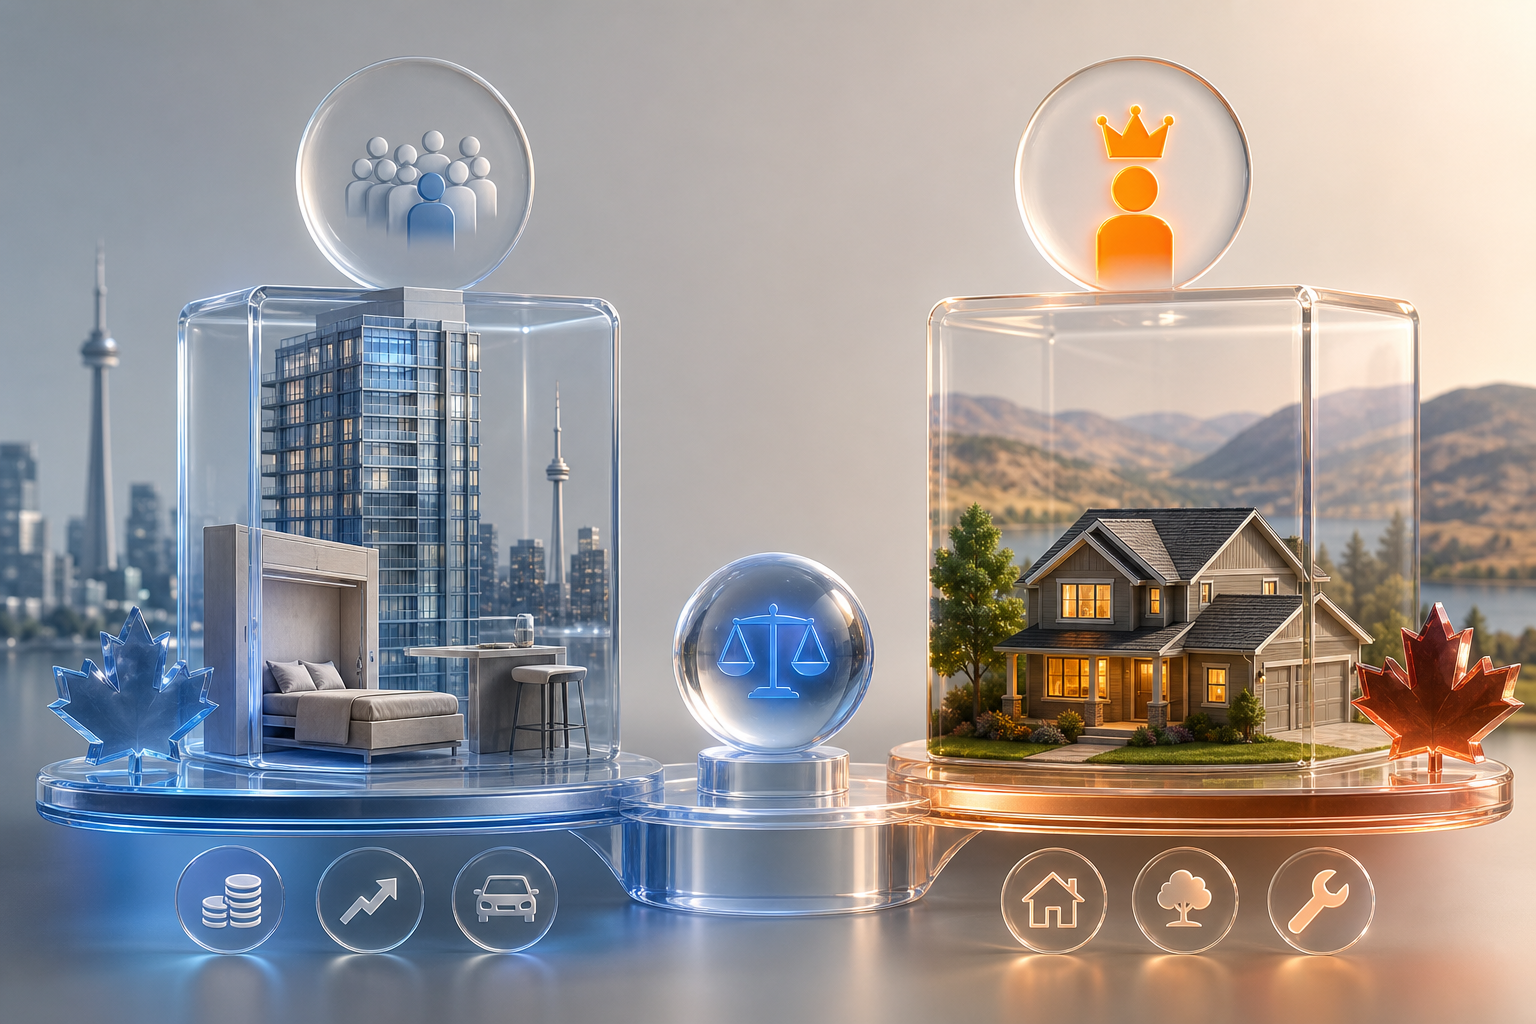

A studio condo in downtown Toronto came with 480 square feet, $650 monthly maintenance, and a parking space that cost extra. The listing showed a Murphy bed and a counter-height table wedged against a window. That same week, a buyer in Kelowna closed on a four-bedroom detached home with a finished basement, a front yard, and a detached garage. Both properties sold for $500,000. The qualification paperwork looked almost identical.
The difference wasn't price. The difference was what the price bought. One buyer got density. The other got square footage. Most shopping begins with a budget number and ends with whatever fits inside that number. That sequence is backward.
The Leverage Shift Buyers Miss
In Toronto, $500,000 in September 2026 puts you at the bottom of the buyer hierarchy. You are shopping entry-level inventory in a market where the benchmark detached home is $993,410. Sellers know your budget before you walk through the door, and they know you don't have much room to move. Asking for repairs, negotiating on closing dates, or requesting a home inspection with contingencies puts you at the back of the line behind buyers with deeper pockets.
In Kelowna, that same $500,000 makes you the premium buyer. You can afford most of what's on the market, which means you dictate terms. Sellers accommodate your timeline. They fix the roof. They include the appliances. The transaction structure bends toward you because you're the one with the money, not the one barely scraping into the market. This isn't a personality difference. It's structural. The amount of capital you control relative to the local price distribution determines whether you negotiate or whether you take what you can get.
What the Same Number Actually Buys
In the Greater Toronto Area, a $500,000 budget typically secures a one-bedroom condo under 600 square feet, often in an aging building where monthly maintenance fees run $850 to $1,100. Those fees reduce your mortgage qualification by roughly $100,000 to $150,000 compared to a freehold property with no monthly fee load. The real carrying cost isn't the mortgage. It's the mortgage plus the fee plus the property tax, and that combination eats discretionary income faster than most first-time buyers anticipate.
In Alberta or Saskatchewan mid-sized cities, $500,000 buys a three-bedroom detached bungalow, sometimes four bedrooms if the property is listed between $485,000 and $515,000. The maintenance responsibility shifts to the homeowner, but there's no monthly fee bleeding the budget. Property taxes in these markets typically run 30 to 50 percent lower than comparable Toronto rates, and parking isn't a separate line item, it's a driveway attached to a house you own outright, land included.
The appreciation story differs too. Condos in high-density markets tend to appreciate when supply is constrained, but the land-to-building ratio works against you. A condo appreciates at the rate of scarcity and demand. A detached home with land appreciates at the rate of land value plus scarcity and demand. Over a decade, that spread compounds.
The Cost No One Factors In
Maintenance fees aren't mortgage payments, so they don't appear in the purchase price. But $900 per month at 5.25 percent over 25 years is equivalent to roughly $150,000 in borrowing power you're not using on the principal asset. A buyer who ignores this treats a $500,000 condo as equivalent to a $500,000 house. It isn't. The condo's true cost to carry resembles a $650,000 freehold mortgage when you add the fees back in.
This is where remorse starts. Two years in, the unit feels smaller. The fees go up. The building needs a special assessment. The equity gain is modest because twenty other identical units listed in the same complex, and now you're competing against yourself to sell. Meanwhile, the buyer in Kelowna has a basement they converted into a rental suite, which covers part of the mortgage.
Where This Leaves You
Some buyers don't have options. The job is in Vancouver. The aging parents are in Ottawa. The custody arrangement requires proximity to a specific school district. Geography binds you, and the strategy has to work within that constraint. Acknowledged.
For everyone else, the question isn't "What can I afford?" The question is "What does this $500,000 need to accomplish?" If the goal is space for a growing family, a home office, or a workshop, buying a condo in a high-cost market delays that goal by five to seven years while you wait for enough equity to trade up. If the goal is proximity to a specific industry, nightlife, or transit hub, the square footage concession might be worth it.
But most buyers don't ask that question. They ask "What's the nicest thing I can buy for $500,000?" and then they buy it without measuring it against the life they're actually trying to build. That's the gap. Not affordability. Alignment.
Read Next
What 27 Rising Stars Under 40 Reveal About Canada's Next Wealth Model
The Deficit Fell $11.6 Billion. Your Mortgage Rate Didn't Get the Memo.
Banks Call It a Transfer Fee, but It Works Like an Exit Penalty
Leveraged Insurance Ends When Regulators See the Downside, Whatever the Math Says