Why You Should Apply for Maximum Disability Coverage, Not Calculate a Target Percentage
A 38-year-old pharmacist in Summerside earning $94,000 sits down with a spreadsheet to work out her disability insurance need. She tallies fixed expenses, estimates what she could cut, stress-tests a few scenarios, lands on 60% income replacement as her target, and applies for $56,400 annual coverage. Two years later she's diagnosed with rheumatoid arthritis severe enough that she can't work the counter anymore. The policy pays. The cheque clears. And six months in, she realizes the 60% she calculated didn't account for the physiotherapy that isn't covered under her employer plan anymore, because she's no longer employed.
The arithmetic was clean, but her disabled life was far messier than the spreadsheet had assumed.
The insurer already did the math
Disability insurers cap coverage to prevent moral hazard. If you could collect more on claim than you earn working, the incentive structure breaks. That ceiling sits somewhere between 60% and 80% of gross income depending on the carrier, the occupation class, and whether other coverage is already in force. It's a hard limit. You cannot over-insure even if you want to.
Which means the question most people ask, "How much disability coverage do I need?", is backwards. The insurer has already answered it. The number they'll approve is the maximum rational coverage for your income and circumstances. Applying for less doesn't make you prudent. It just leaves a gap.
Expenses don't compress the way income does
The 60%-is-fine logic assumes that life on claim is life-but-cheaper. No commuting costs, maybe. No work wardrobe. But rent doesn't drop when you're disabled. Neither does your mortgage, your property tax, or your car payment. Groceries don't care. If you have kids, their costs hold or climb.
The new costs surface slowly. Medication not covered under a group plan you've lost. Home modifications. Transportation when you can't drive yourself. Rehab that OHIP (or the provincial equivalent) won't fund. Somebody to mow the lawn, shovel the driveway, carry the groceries up the stairs.
None of this shows up in a pre-claim budget exercise because you're healthy when you're filling out the application. You're guessing at a life you haven't lived yet. Meanwhile, the insurer's actuarial table is working from a dataset that includes actual claims. They've seen what disabled policyholders need. That's where the cap comes from.
Undershooting costs more than over-applying
Applying for maximum coverage and getting declined costs you nothing. Applying for less than maximum and running into a gap five years into a claim costs you the difference between what you're collecting and what you actually need, compounded across however many years the disability lasts.
Worst case if you apply high: the underwriter scales it back and you get what their guidelines allow. Worst case if you apply low: you're stuck with it, because you can't typically increase an in-force policy's benefit without going through underwriting again, and if you're already claiming or dealing with a new diagnosis, you're not getting better terms.
The 24% of insured Canadians who lack confidence in their life insurance coverage, according to a 2026 MoneySense survey, underapplied and then circumstances shifted before they could fix it.
Start at the ceiling, not the middle
Apply for the maximum the insurer will approve. Let them run the underwriting. Let them tell you what the cap is. If your budget says you can't afford the premium on maximum coverage, drop riders or extend the waiting period rather than cutting the benefit. But start the conversation at the top.
The question isn't what percentage feels right. It's whether the number that comes back covers the version of your life that happens when you can't work. You won't know that version until you're living it. The insurer has already built in the guardrails. Use them.



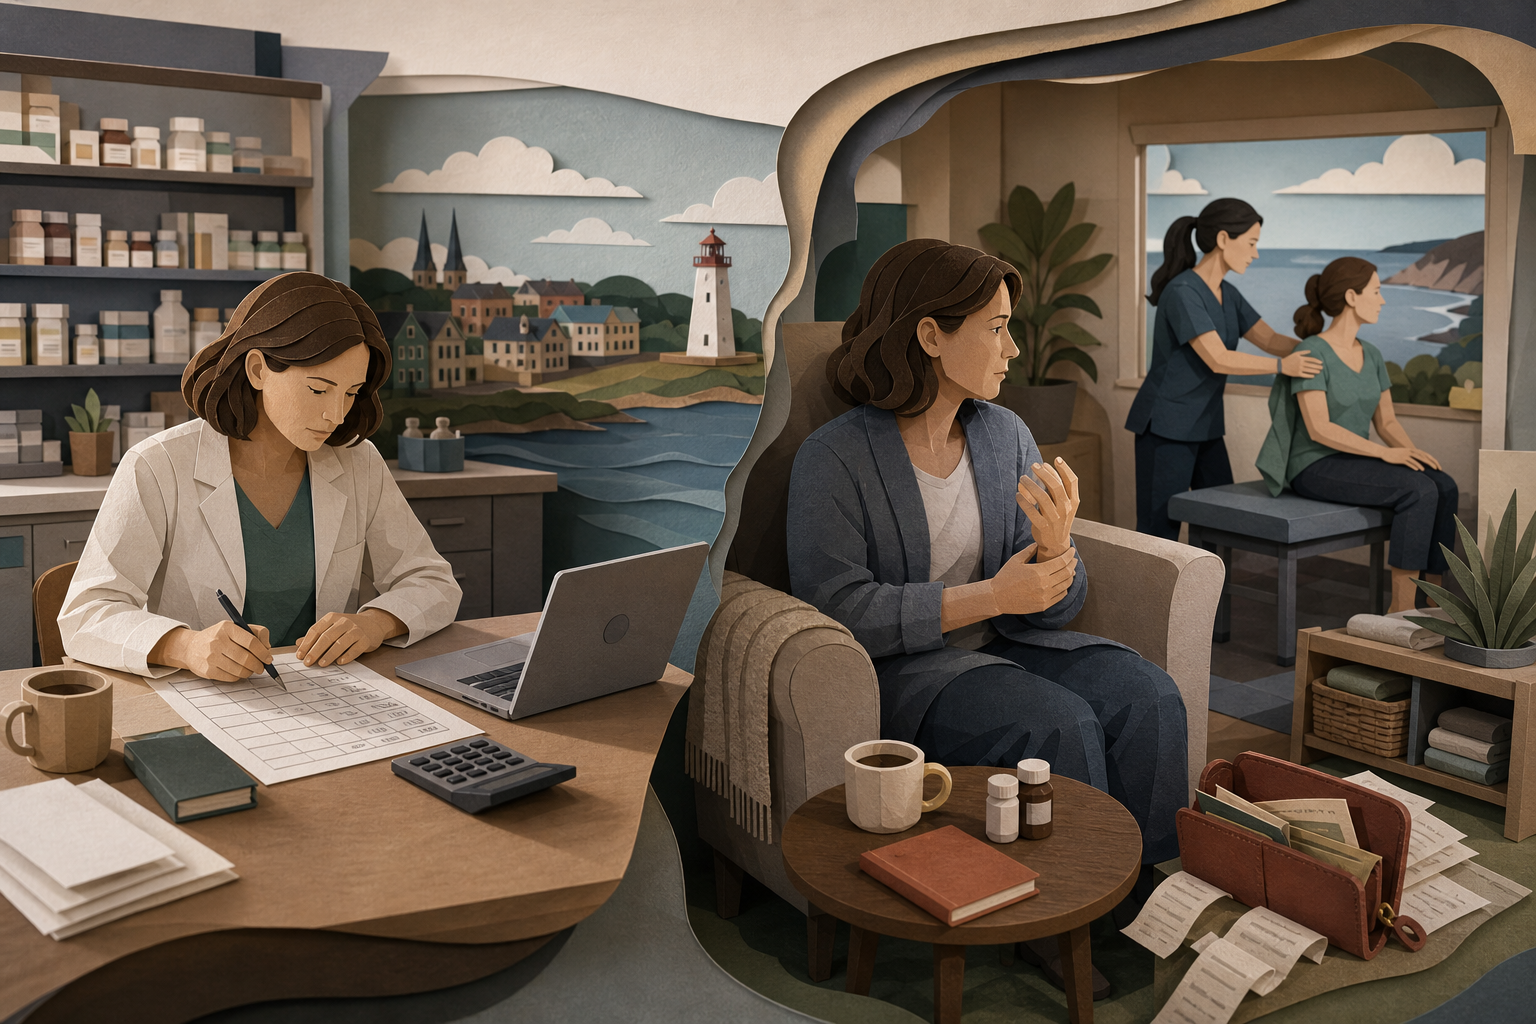

A 38-year-old pharmacist in Summerside earning $94,000 sits down with a spreadsheet to work out her disability insurance need. She tallies fixed expenses, estimates what she could cut, stress-tests a few scenarios, lands on 60% income replacement as her target, and applies for $56,400 annual coverage. Two years later she's diagnosed with rheumatoid arthritis severe enough that she can't work the counter anymore. The policy pays. The cheque clears. And six months in, she realizes the 60% she calculated didn't account for the physiotherapy that isn't covered under her employer plan anymore, because she's no longer employed.
The arithmetic was clean, but her disabled life was far messier than the spreadsheet had assumed.
The insurer already did the math
Disability insurers cap coverage to prevent moral hazard. If you could collect more on claim than you earn working, the incentive structure breaks. That ceiling sits somewhere between 60% and 80% of gross income depending on the carrier, the occupation class, and whether other coverage is already in force. It's a hard limit. You cannot over-insure even if you want to.
Which means the question most people ask, "How much disability coverage do I need?", is backwards. The insurer has already answered it. The number they'll approve is the maximum rational coverage for your income and circumstances. Applying for less doesn't make you prudent. It just leaves a gap.
Expenses don't compress the way income does
The 60%-is-fine logic assumes that life on claim is life-but-cheaper. No commuting costs, maybe. No work wardrobe. But rent doesn't drop when you're disabled. Neither does your mortgage, your property tax, or your car payment. Groceries don't care. If you have kids, their costs hold or climb.
The new costs surface slowly. Medication not covered under a group plan you've lost. Home modifications. Transportation when you can't drive yourself. Rehab that OHIP (or the provincial equivalent) won't fund. Somebody to mow the lawn, shovel the driveway, carry the groceries up the stairs.
None of this shows up in a pre-claim budget exercise because you're healthy when you're filling out the application. You're guessing at a life you haven't lived yet. Meanwhile, the insurer's actuarial table is working from a dataset that includes actual claims. They've seen what disabled policyholders need. That's where the cap comes from.
Undershooting costs more than over-applying
Applying for maximum coverage and getting declined costs you nothing. Applying for less than maximum and running into a gap five years into a claim costs you the difference between what you're collecting and what you actually need, compounded across however many years the disability lasts.
Worst case if you apply high: the underwriter scales it back and you get what their guidelines allow. Worst case if you apply low: you're stuck with it, because you can't typically increase an in-force policy's benefit without going through underwriting again, and if you're already claiming or dealing with a new diagnosis, you're not getting better terms.
The 24% of insured Canadians who lack confidence in their life insurance coverage, according to a 2026 MoneySense survey, underapplied and then circumstances shifted before they could fix it.
Start at the ceiling, not the middle
Apply for the maximum the insurer will approve. Let them run the underwriting. Let them tell you what the cap is. If your budget says you can't afford the premium on maximum coverage, drop riders or extend the waiting period rather than cutting the benefit. But start the conversation at the top.
The question isn't what percentage feels right. It's whether the number that comes back covers the version of your life that happens when you can't work. You won't know that version until you're living it. The insurer has already built in the guardrails. Use them.
Read Next
What 27 Rising Stars Under 40 Reveal About Canada's Next Wealth Model
The Deficit Fell $11.6 Billion. Your Mortgage Rate Didn't Get the Memo.
Banks Call It a Transfer Fee, but It Works Like an Exit Penalty
Leveraged Insurance Ends When Regulators See the Downside, Whatever the Math Says