Why Most Canadian Mortgages Can't Run the Smith Manoeuvre™ (And Lenders Won't Tell You)
A 47-year-old accountant in Vaughan refinanced in early 2024 to "set up the Smith Manoeuvre™." Six months later, she called her broker confused. Her mortgage statement showed $14,000 of principal paid down, but her HELOC limit hadn't moved. The bank told her she'd need to apply for a limit increase. That's when she learned her product wasn't actually readvanceable.
What "Readvanceable" Actually Means
The Smith Manoeuvre™ requires synchronization between two moving parts: every dollar of mortgage principal you pay down must automatically free up a dollar of HELOC room the same month. No application. No call to the branch. The system does it.
Most "mortgage plus line of credit" bundles don't work this way. The HELOC sits at a fixed limit, often 65% of your home's value at closing, and stays there until you ask for more. When you ask, the lender treats it like a new credit decision: they pull credit, verify income, sometimes order an appraisal. The timeline stretches weeks, and the approval isn't guaranteed. By then, the monthly discipline the strategy needs has collapsed.
True readvanceable products link the two accounts inside the bank's core system. When your mortgage payment posts, the HELOC limit adjusts the next business day. RBC's Homeline Plan, Scotia's Total Equity Plan, and BMO's Readiline work this way. Most other products marketed as "combo mortgages" do not, even when the brochure shows both products on the same page.
The Collateral Charge Trap
Readvanceable mortgages are registered as collateral charges. That matters at renewal.
A standard-charge mortgage can be transferred to another lender with an electronic switch. No legal fees, minimal paperwork. A collateral charge requires a full discharge and re-registration if you leave. (cite index="10-2">Legal costs typically range from $500 to $1,500 (legal/notary fees) or $800–$2,000+ (total switch costs), depending on province and lender. Most borrowers don't know this when they sign, and by renewal, the original lender knows you're effectively locked in. They quote higher rates because switching hurts.
The structure gives the lender pricing power for the life of the loan. That's part of why banks offer readvanceable products in the first place: the collateral charge creates future revenue the standard mortgage doesn't. It's not disclosed as a trade-off.
The Three-Account Setup Nobody Explains
A working Smith Manoeuvre™ implementation uses three buckets, not two. The mortgage. The readvanceable HELOC tied to mortgage pay-down, used only for income-producing investments. And a third HELOC segment for everything else, emergencies, renovations, short-term needs.
Without the third bucket, borrowers co-mingle. They use the investment HELOC for a car repair or a vacation, and now the interest deductibility calculation is polluted. The Canada Revenue Agency audits based on "direct use," meaning every draw has to trace to an eligible investment. A $4,000 vacation buried in $60,000 of investment draws doesn't void the whole claim, but it creates a headache at tax time that most accountants bill hourly to untangle.
The third account firewall prevents this. Few brokers set it up because it requires a longer conversation at origination and slightly more documentation. The borrower finds out the hard way two years in.
Why Lenders Stay Quiet
A manual HELOC generates more touchpoints. Every time you want to access equity, the bank runs credit, collects documents, charges a fee. A readvanceable product automates that access, which is good for you and bad for the bank's fee line.
Branch staff aren't trained to distinguish between the two structures. Most will confirm you have "a line of credit attached" and assume that's sufficient. Mortgage specialists at the big banks know the difference but aren't incentivized to educate unless the borrower asks the specific question: "Does the HELOC limit increase automatically as I pay down the mortgage, or do I need to apply?"
The answer determines whether the product works for tax-deductible debt conversion. One word, "automatically", is the entire test. Most borrowers never ask it.



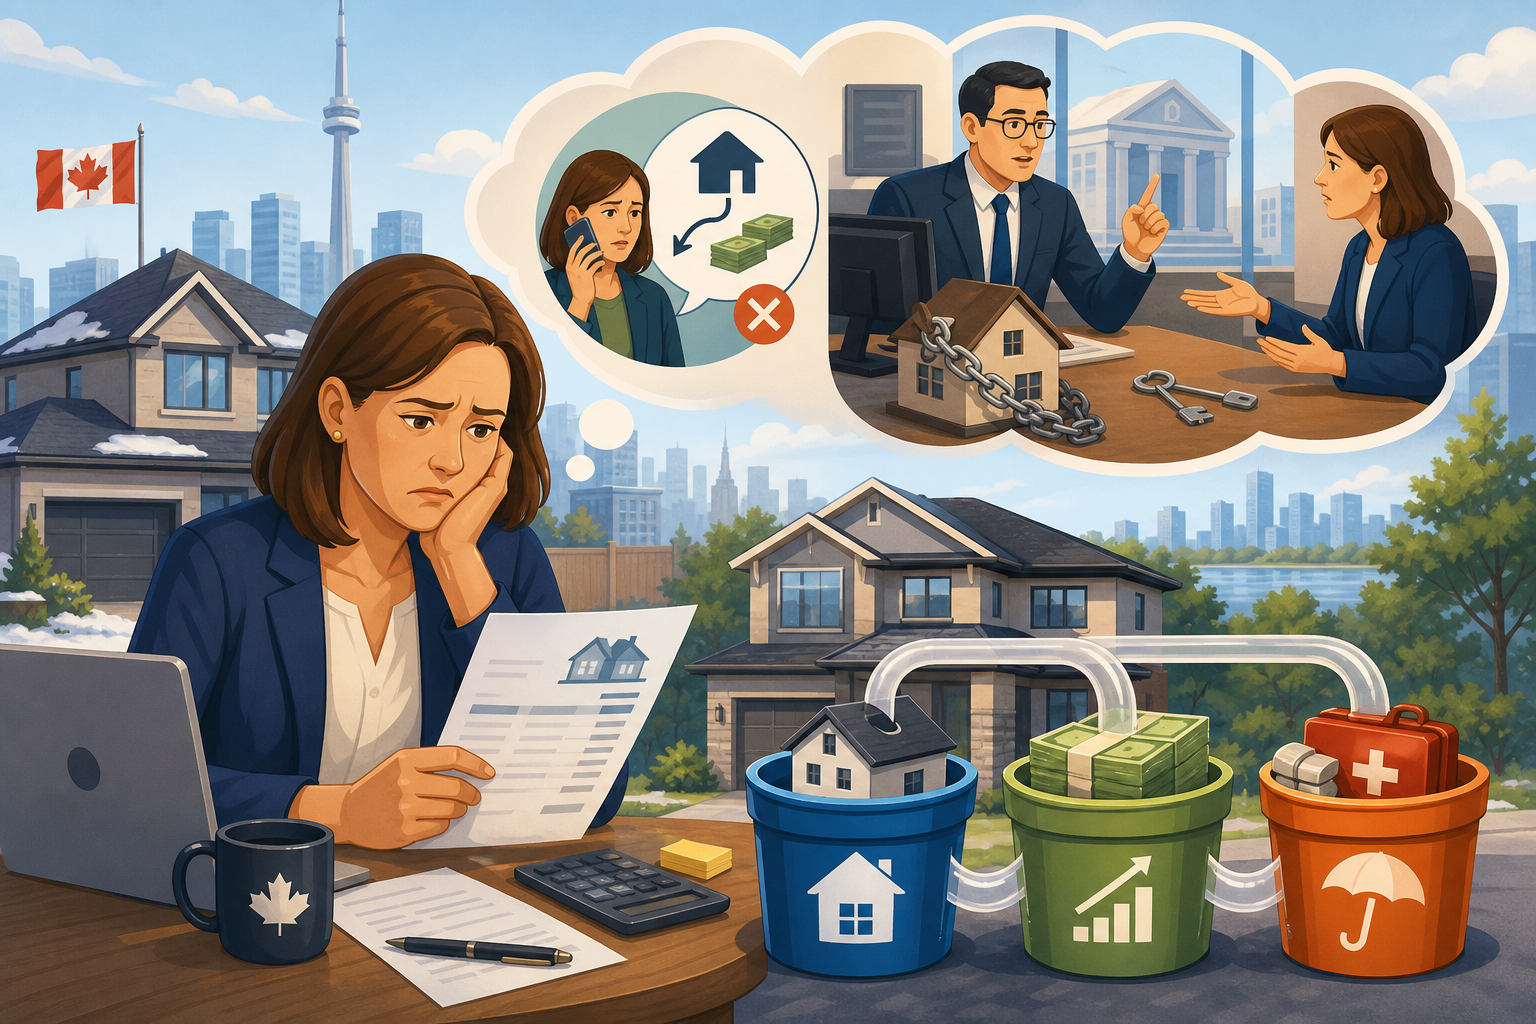

A 47-year-old accountant in Vaughan refinanced in early 2024 to "set up the Smith Manoeuvre™." Six months later, she called her broker confused. Her mortgage statement showed $14,000 of principal paid down, but her HELOC limit hadn't moved. The bank told her she'd need to apply for a limit increase. That's when she learned her product wasn't actually readvanceable.
What "Readvanceable" Actually Means
The Smith Manoeuvre™ requires synchronization between two moving parts: every dollar of mortgage principal you pay down must automatically free up a dollar of HELOC room the same month. No application. No call to the branch. The system does it.
Most "mortgage plus line of credit" bundles don't work this way. The HELOC sits at a fixed limit, often 65% of your home's value at closing, and stays there until you ask for more. When you ask, the lender treats it like a new credit decision: they pull credit, verify income, sometimes order an appraisal. The timeline stretches weeks, and the approval isn't guaranteed. By then, the monthly discipline the strategy needs has collapsed.
True readvanceable products link the two accounts inside the bank's core system. When your mortgage payment posts, the HELOC limit adjusts the next business day. RBC's Homeline Plan, Scotia's Total Equity Plan, and BMO's Readiline work this way. Most other products marketed as "combo mortgages" do not, even when the brochure shows both products on the same page.
The Collateral Charge Trap
Readvanceable mortgages are registered as collateral charges. That matters at renewal.
A standard-charge mortgage can be transferred to another lender with an electronic switch. No legal fees, minimal paperwork. A collateral charge requires a full discharge and re-registration if you leave. (cite index="10-2">Legal costs typically range from $500 to $1,500 (legal/notary fees) or $800–$2,000+ (total switch costs), depending on province and lender. Most borrowers don't know this when they sign, and by renewal, the original lender knows you're effectively locked in. They quote higher rates because switching hurts.
The structure gives the lender pricing power for the life of the loan. That's part of why banks offer readvanceable products in the first place: the collateral charge creates future revenue the standard mortgage doesn't. It's not disclosed as a trade-off.
The Three-Account Setup Nobody Explains
A working Smith Manoeuvre™ implementation uses three buckets, not two. The mortgage. The readvanceable HELOC tied to mortgage pay-down, used only for income-producing investments. And a third HELOC segment for everything else, emergencies, renovations, short-term needs.
Without the third bucket, borrowers co-mingle. They use the investment HELOC for a car repair or a vacation, and now the interest deductibility calculation is polluted. The Canada Revenue Agency audits based on "direct use," meaning every draw has to trace to an eligible investment. A $4,000 vacation buried in $60,000 of investment draws doesn't void the whole claim, but it creates a headache at tax time that most accountants bill hourly to untangle.
The third account firewall prevents this. Few brokers set it up because it requires a longer conversation at origination and slightly more documentation. The borrower finds out the hard way two years in.
Why Lenders Stay Quiet
A manual HELOC generates more touchpoints. Every time you want to access equity, the bank runs credit, collects documents, charges a fee. A readvanceable product automates that access, which is good for you and bad for the bank's fee line.
Branch staff aren't trained to distinguish between the two structures. Most will confirm you have "a line of credit attached" and assume that's sufficient. Mortgage specialists at the big banks know the difference but aren't incentivized to educate unless the borrower asks the specific question: "Does the HELOC limit increase automatically as I pay down the mortgage, or do I need to apply?"
The answer determines whether the product works for tax-deductible debt conversion. One word, "automatically", is the entire test. Most borrowers never ask it.
Sources
Read Next
What 27 Rising Stars Under 40 Reveal About Canada's Next Wealth Model
The Deficit Fell $11.6 Billion. Your Mortgage Rate Didn't Get the Memo.
Banks Call It a Transfer Fee, but It Works Like an Exit Penalty
Leveraged Insurance Ends When Regulators See the Downside, Whatever the Math Says