Which Refinancing Moves Still Work Under a 20% Equity Floor on Re-advanceable Mortgages
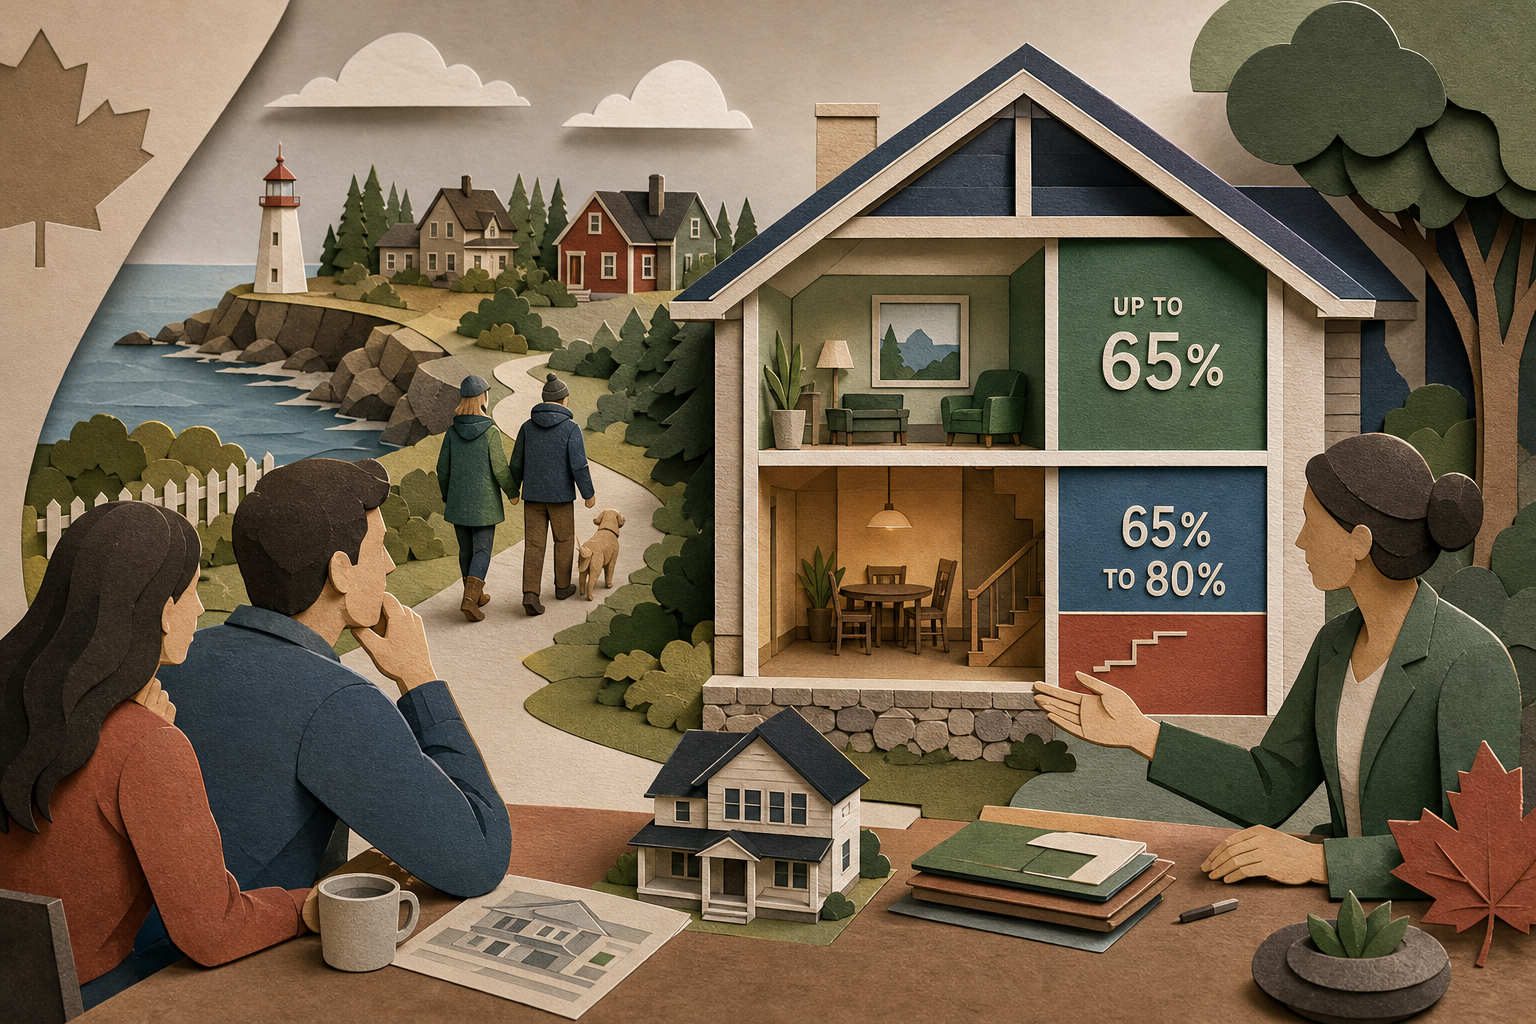
Most re-advanceable mortgages in Canada are now built in two layers. Up to 65 percent of your home's value can sit in a revolving line of credit that you can draw, repay and draw again. The slice between 65 and 80 percent has to amortize like an ordinary mortgage. That second layer is what most people miss when they first hear that 20 percent equity "qualifies" them, and it shapes nearly every refinancing decision that follows.
Why the floor sits at 20 percent
A re-advanceable mortgage combines a standard mortgage with a home equity line of credit. As each payment reduces the mortgage principal, the credit limit on the line grows by the same amount. This is the mechanism behind the Smith Manoeuvre™. You borrow back the principal you just repaid, invest it in a non-registered account, and the interest on that borrowed portion becomes potentially deductible.
Lenders require at least 20 percent equity to set one up. The reason is structural. Below that line, a loan needs mortgage insurance. A refinance can't be insured, so the uninsured rules apply, and those cap total borrowing at 80 percent of the home's value. Under OSFI's Guideline B-20, the revolving part stops at 65 percent. Anything above that has to be repaid on a schedule.
Here is an illustration with round numbers. On a home appraised at $400,000, total borrowing tops out at $320,000. Only $260,000 of that can be revolving credit. If your current mortgage is $300,000, you qualify. But the first $40,000 of principal you pay down won't free up room in the line in any way that helps a Smith Manoeuvre™ plan, because it sits in the required amortizing layer.
Who feels this most
Refinancers just under the line. Many Charlottetown homeowners who bought between 2020 and 2022 are only now reaching 20 percent equity, through a mix of regular paydown and modest price growth. If you are at 15 or 18 percent, a conventional refinance isn't available yet. The alternatives, such as a private second mortgage, usually cost far more than waiting another year or two.
Smith Manoeuvre™ builders. The value of the strategy depends on your marginal tax rate. For higher earners on the Island, the combined federal and provincial rate is roughly half of each additional dollar. That gap between non-deductible mortgage interest and deductible investment interest is the reason to restructure at all. Starting right at 20 percent equity means starting with the amortizing slice in the way, so expect a slower build in the early years.
Debt consolidators. Having the equity doesn't guarantee approval. Uninsured borrowers must qualify at the higher of their contract rate plus two percentage points, or 5.25 percent. Folding car loans and credit cards into the mortgage raises the payment you are tested against, and that can cap the amount even when the appraisal supports more.
Business owners. For self-employed clients, crossing 20 percent often opens the door to cash flow damming. This approach directs business revenue toward the mortgage and runs business expenses through the line, so personal debt gradually becomes debt tied to income-producing activity. It only works once the re-advanceable structure exists.
"But I got one with less equity"
Some people did, or think they did. Usually one of three things explains it. The account may have been opened at purchase with 20 percent down. The line may have been set up with a limit near zero and expanded later. Or the lender may have been a provincially regulated credit union with its own internal policy, though most have aligned with the 20 percent standard. Existing borrowers can also find the re-advance feature paused if a lower valuation or slow paydown pushes them back above 65 percent. The product can stay in place while the strategy stalls inside it.
When you are short of the line
Start with an equity audit before any formal application. In a small market like PEI, one weak comparable sale can pull an appraisal down enough to sink a refinance, so it helps to know your realistic range first. If you are close, prepayments are often the cleanest bridge. Many mortgages allow lump-sum payments of up to 20 percent of the original principal each year, or payment increases of a similar size. Directing a bonus or tax refund there moves you toward the floor and lowers your future interest at the same time.
If you are further away, the useful work is planning rather than borrowing. That means choosing a lender whose re-advanceable product you will eventually want, timing your renewal so you aren't locked out by a penalty, and sizing the plan around the 65 percent revolving limit rather than the 80 percent headline. Once that structure is mapped, the day you cross 20 percent is just the start date.




Most re-advanceable mortgages in Canada are now built in two layers. Up to 65 percent of your home's value can sit in a revolving line of credit that you can draw, repay and draw again. The slice between 65 and 80 percent has to amortize like an ordinary mortgage. That second layer is what most people miss when they first hear that 20 percent equity "qualifies" them, and it shapes nearly every refinancing decision that follows.
Why the floor sits at 20 percent
A re-advanceable mortgage combines a standard mortgage with a home equity line of credit. As each payment reduces the mortgage principal, the credit limit on the line grows by the same amount. This is the mechanism behind the Smith Manoeuvre™. You borrow back the principal you just repaid, invest it in a non-registered account, and the interest on that borrowed portion becomes potentially deductible.
Lenders require at least 20 percent equity to set one up. The reason is structural. Below that line, a loan needs mortgage insurance. A refinance can't be insured, so the uninsured rules apply, and those cap total borrowing at 80 percent of the home's value. Under OSFI's Guideline B-20, the revolving part stops at 65 percent. Anything above that has to be repaid on a schedule.
Here is an illustration with round numbers. On a home appraised at $400,000, total borrowing tops out at $320,000. Only $260,000 of that can be revolving credit. If your current mortgage is $300,000, you qualify. But the first $40,000 of principal you pay down won't free up room in the line in any way that helps a Smith Manoeuvre™ plan, because it sits in the required amortizing layer.
Who feels this most
Refinancers just under the line. Many Charlottetown homeowners who bought between 2020 and 2022 are only now reaching 20 percent equity, through a mix of regular paydown and modest price growth. If you are at 15 or 18 percent, a conventional refinance isn't available yet. The alternatives, such as a private second mortgage, usually cost far more than waiting another year or two.
Smith Manoeuvre™ builders. The value of the strategy depends on your marginal tax rate. For higher earners on the Island, the combined federal and provincial rate is roughly half of each additional dollar. That gap between non-deductible mortgage interest and deductible investment interest is the reason to restructure at all. Starting right at 20 percent equity means starting with the amortizing slice in the way, so expect a slower build in the early years.
Debt consolidators. Having the equity doesn't guarantee approval. Uninsured borrowers must qualify at the higher of their contract rate plus two percentage points, or 5.25 percent. Folding car loans and credit cards into the mortgage raises the payment you are tested against, and that can cap the amount even when the appraisal supports more.
Business owners. For self-employed clients, crossing 20 percent often opens the door to cash flow damming. This approach directs business revenue toward the mortgage and runs business expenses through the line, so personal debt gradually becomes debt tied to income-producing activity. It only works once the re-advanceable structure exists.
"But I got one with less equity"
Some people did, or think they did. Usually one of three things explains it. The account may have been opened at purchase with 20 percent down. The line may have been set up with a limit near zero and expanded later. Or the lender may have been a provincially regulated credit union with its own internal policy, though most have aligned with the 20 percent standard. Existing borrowers can also find the re-advance feature paused if a lower valuation or slow paydown pushes them back above 65 percent. The product can stay in place while the strategy stalls inside it.
When you are short of the line
Start with an equity audit before any formal application. In a small market like PEI, one weak comparable sale can pull an appraisal down enough to sink a refinance, so it helps to know your realistic range first. If you are close, prepayments are often the cleanest bridge. Many mortgages allow lump-sum payments of up to 20 percent of the original principal each year, or payment increases of a similar size. Directing a bonus or tax refund there moves you toward the floor and lowers your future interest at the same time.
If you are further away, the useful work is planning rather than borrowing. That means choosing a lender whose re-advanceable product you will eventually want, timing your renewal so you aren't locked out by a penalty, and sizing the plan around the 65 percent revolving limit rather than the 80 percent headline. Once that structure is mapped, the day you cross 20 percent is just the start date.
Read Next
What 27 Rising Stars Under 40 Reveal About Canada's Next Wealth Model
The Deficit Fell $11.6 Billion. Your Mortgage Rate Didn't Get the Memo.
Banks Call It a Transfer Fee, but It Works Like an Exit Penalty
Leveraged Insurance Ends When Regulators See the Downside, Whatever the Math Says