Eight Smith Manoeuvre™ Variations Ranked by Risk and Realism
Most homeowners who hear about the Smith Manoeuvre™ picture a single strategy: you pay down the mortgage, borrow back the principal, invest it, and deduct the interest. That description is accurate the way a blueprint of a hammer is accurate. It names the tool but says nothing about what you can build with it.
The Smith Manoeuvre™ is a structural framework with at least eight distinct variations, each designed for a different cash flow position, risk appetite, and stage of wealth accumulation. The difference between them is not cosmetic. A 38-year-old engineer with $200,000 in stagnant equity and no consumer debt faces a different challenge than a 52-year-old couple carrying $40,000 in credit card balances at 19.9% or a retiree with a paid-off house and a $1.2 million taxable portfolio. The variation that works for one will either underwhelm or overleverage the others.
Plain Jane: The Foundational Case
The "Plain Jane" is the base case. You make your regular mortgage payment. The principal portion of that payment immediately unlocks equivalent room in the readvanceable home equity line of credit. You borrow that amount and invest it in income-producing assets held in a non-registered account. The interest on the borrowed funds is tax-deductible because the money was used to earn income. This is the only variation that requires no lump-sum moves, no portfolio liquidation, and no external borrowing. It is dollar-cost averaging funded by debt conversion rather than new cash flow.
The time horizon is long. If your monthly principal payment is $800, you are unlocking $9,600 of investment room per year. Over 25 years, assuming no acceleration, that is $240,000 of converted debt. The math unfolds slowly. This is the variation that works when simplicity and consistency matter more than speed.
Singleton Shuffle: Instant Conversion for Existing Portfolios
The "Singleton Shuffle" solves a different problem. You already own a taxable portfolio of stocks or mutual funds. The portfolio is funded with after-tax dollars, and the debt on your mortgage is non-deductible. The shuffle works like this: liquidate the portfolio, use the proceeds to prepay the mortgage principal, and immediately reborrow the same amount from the HELOC to repurchase the investments. Your market exposure does not change. Your debt structure does.
The benefit is speed. A homeowner with $150,000 in a non-registered account can convert that entire amount into tax-deductible debt in a single transaction instead of waiting 15 years for monthly principal payments to unlock equivalent room. The cost is the capital gains tax triggered by the liquidation. If the portfolio has appreciated significantly, that tax bill can be substantial. The strategy makes sense when the long-term value of the interest deduction outweighs the one-time tax hit. Recent changes to OSFI rules around loan-to-value ratios above 65% have added friction to how lenders structure readvanceable products, but the underlying logic remains intact.
Top-Up: Deploying Stagnant Equity
The "Top-Up" variation addresses appreciation. A homeowner who bought in Halifax in 2018 for $320,000 and now owns a property worth $480,000 has $160,000 in equity doing nothing. The Top-Up allows you to borrow a lump sum against that equity at inception and invest it immediately, rather than waiting for mortgage payments to slowly unlock the room. The borrowed amount is invested in income-producing assets, and the interest is deductible. Compounding starts on the full amount from day one.
The risk is larger exposure to market downturns early in the strategy. A 15% market drop on $150,000 deployed upfront is $22,500. The same drop on monthly $800 investments spread over five years touches far less capital. The Top-Up is an acceleration tool for homeowners who understand that leverage magnifies both gains and losses and who have the cash flow to service the HELOC interest without stress.
Debt Miracle: Consolidation as the Entry Point
The "Debt Miracle" starts with high-interest consumer debt. A household carrying $35,000 in credit card balances at 19.9% and a car loan at 7.8% can consolidate those balances into the readvanceable mortgage structure, where the effective rate might be 6.2%. The savings on interest cost free up cash flow, which accelerates mortgage principal paydown. As the mortgage principal drops, HELOC room opens, and that room is borrowed to invest.
The consolidation step is the setup. The strategy begins once the HELOC room is used for investment borrowing rather than consumption borrowing. The mistake is treating the Debt Miracle as a way to keep spending. The discipline is treating it as a one-time reset that redirects interest savings toward wealth-building.
Using Dividends to Accelerate Paydown
The "Using Dividends" variation redirects portfolio income back into the mortgage instead of reinvesting it automatically. A $120,000 portfolio yielding 4% annually generates $4,800 in dividends. That $4,800 pays down the mortgage principal, which unlocks $4,800 of new HELOC room, which is immediately borrowed and reinvested. The cycle compounds.
The benefit is faster debt conversion. The cost is tax complexity. Dividends are taxable income in the year they are received, and the marginal tax rate on Canadian eligible dividends can reach 39–46% depending on province and income level. The strategy works when the household has cash flow to cover the tax bill without touching the reinvested capital. It fails when the tax liability forces premature liquidation.
Smith Snider: Retirement De-accumulation
The "Smith Snider" flips the strategy for retirees. Instead of building a leveraged portfolio, it draws income from an existing one without triggering large capital gains spikes. A retiree with a $1.1 million taxable portfolio can borrow against home equity to fund living expenses, leaving the portfolio intact to compound. The borrowed funds are used to earn income, so the interest remains deductible. Over time, the retiree liquidates portions of the portfolio gradually, smoothing the tax burden across multiple years rather than concentrating it.
This is a tax-efficient withdrawal strategy. The risk is rising interest rates making the borrowed funds more expensive than the portfolio's after-tax return. It works when rates are low and the portfolio generates steady dividends and distributions, not speculation.
Rempel Maximum and Triple Top-Up: The Aggressive Outliers
The "Rempel Maximum" borrows a large lump sum upfront using structured investment loans alongside home equity, maximizing market exposure from day one. The "Triple Top-Up" layers borrowed home equity, traditional investment loans, and systematic recycling of tax refunds and portfolio distributions into a continuous reinvestment engine. Both require dedicated financial planning, tax coordination, and the psychological capacity to hold leveraged positions through multi-year downturns.
These are advanced tools for investors who have already succeeded with simpler variations and who are pursuing marginal gains in tax efficiency. Most working professionals will never need them.
Risk, Ranked
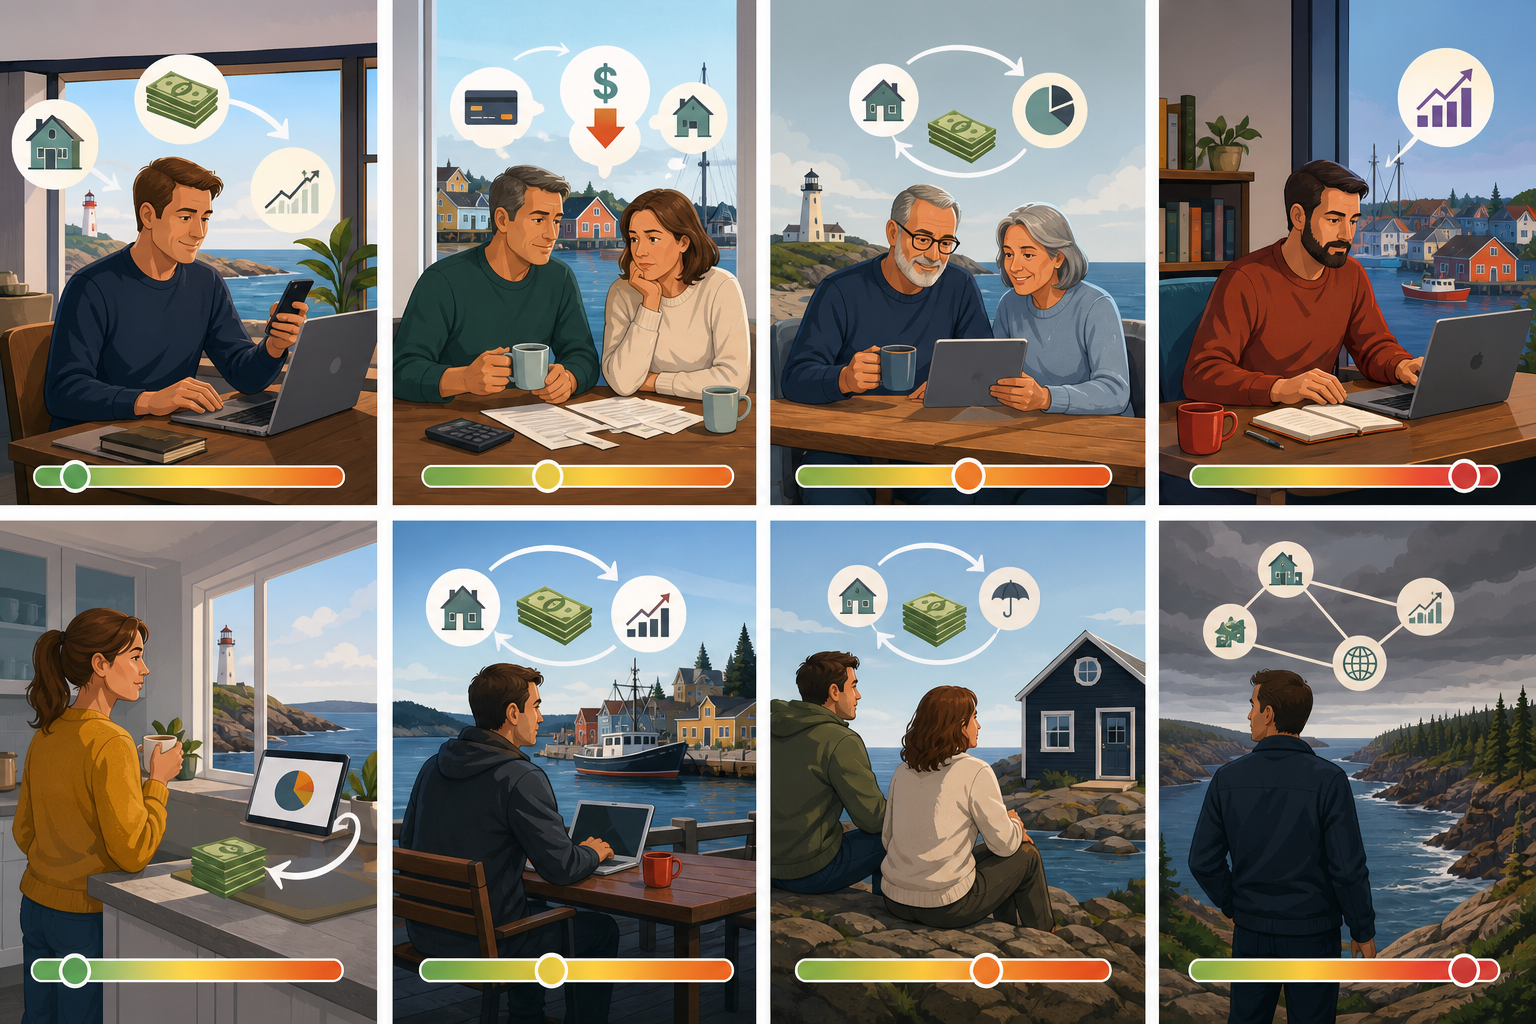
The Plain Jane carries the least risk because it moves slowly and requires no lump-sum decisions. The Singleton Shuffle and Debt Miracle are low-risk if the entry conditions are clean. The Top-Up and Using Dividends increase risk by adding lump-sum exposure or tax complexity. The Rempel Maximum and Triple Top-Up are high-risk because they assume the investor can sustain maximum leverage without panic-selling during corrections. The Smith Snider sits apart: low market risk, high interest-rate risk.
Choose the variation that fits the household's actual cash flow, the investor's actual risk tolerance, and the timeline that matches when the money will be needed.




Most homeowners who hear about the Smith Manoeuvre™ picture a single strategy: you pay down the mortgage, borrow back the principal, invest it, and deduct the interest. That description is accurate the way a blueprint of a hammer is accurate. It names the tool but says nothing about what you can build with it.
The Smith Manoeuvre™ is a structural framework with at least eight distinct variations, each designed for a different cash flow position, risk appetite, and stage of wealth accumulation. The difference between them is not cosmetic. A 38-year-old engineer with $200,000 in stagnant equity and no consumer debt faces a different challenge than a 52-year-old couple carrying $40,000 in credit card balances at 19.9% or a retiree with a paid-off house and a $1.2 million taxable portfolio. The variation that works for one will either underwhelm or overleverage the others.
Plain Jane: The Foundational Case
The "Plain Jane" is the base case. You make your regular mortgage payment. The principal portion of that payment immediately unlocks equivalent room in the readvanceable home equity line of credit. You borrow that amount and invest it in income-producing assets held in a non-registered account. The interest on the borrowed funds is tax-deductible because the money was used to earn income. This is the only variation that requires no lump-sum moves, no portfolio liquidation, and no external borrowing. It is dollar-cost averaging funded by debt conversion rather than new cash flow.
The time horizon is long. If your monthly principal payment is $800, you are unlocking $9,600 of investment room per year. Over 25 years, assuming no acceleration, that is $240,000 of converted debt. The math unfolds slowly. This is the variation that works when simplicity and consistency matter more than speed.
Singleton Shuffle: Instant Conversion for Existing Portfolios
The "Singleton Shuffle" solves a different problem. You already own a taxable portfolio of stocks or mutual funds. The portfolio is funded with after-tax dollars, and the debt on your mortgage is non-deductible. The shuffle works like this: liquidate the portfolio, use the proceeds to prepay the mortgage principal, and immediately reborrow the same amount from the HELOC to repurchase the investments. Your market exposure does not change. Your debt structure does.
The benefit is speed. A homeowner with $150,000 in a non-registered account can convert that entire amount into tax-deductible debt in a single transaction instead of waiting 15 years for monthly principal payments to unlock equivalent room. The cost is the capital gains tax triggered by the liquidation. If the portfolio has appreciated significantly, that tax bill can be substantial. The strategy makes sense when the long-term value of the interest deduction outweighs the one-time tax hit. Recent changes to OSFI rules around loan-to-value ratios above 65% have added friction to how lenders structure readvanceable products, but the underlying logic remains intact.
Top-Up: Deploying Stagnant Equity
The "Top-Up" variation addresses appreciation. A homeowner who bought in Halifax in 2018 for $320,000 and now owns a property worth $480,000 has $160,000 in equity doing nothing. The Top-Up allows you to borrow a lump sum against that equity at inception and invest it immediately, rather than waiting for mortgage payments to slowly unlock the room. The borrowed amount is invested in income-producing assets, and the interest is deductible. Compounding starts on the full amount from day one.
The risk is larger exposure to market downturns early in the strategy. A 15% market drop on $150,000 deployed upfront is $22,500. The same drop on monthly $800 investments spread over five years touches far less capital. The Top-Up is an acceleration tool for homeowners who understand that leverage magnifies both gains and losses and who have the cash flow to service the HELOC interest without stress.
Debt Miracle: Consolidation as the Entry Point
The "Debt Miracle" starts with high-interest consumer debt. A household carrying $35,000 in credit card balances at 19.9% and a car loan at 7.8% can consolidate those balances into the readvanceable mortgage structure, where the effective rate might be 6.2%. The savings on interest cost free up cash flow, which accelerates mortgage principal paydown. As the mortgage principal drops, HELOC room opens, and that room is borrowed to invest.
The consolidation step is the setup. The strategy begins once the HELOC room is used for investment borrowing rather than consumption borrowing. The mistake is treating the Debt Miracle as a way to keep spending. The discipline is treating it as a one-time reset that redirects interest savings toward wealth-building.
Using Dividends to Accelerate Paydown
The "Using Dividends" variation redirects portfolio income back into the mortgage instead of reinvesting it automatically. A $120,000 portfolio yielding 4% annually generates $4,800 in dividends. That $4,800 pays down the mortgage principal, which unlocks $4,800 of new HELOC room, which is immediately borrowed and reinvested. The cycle compounds.
The benefit is faster debt conversion. The cost is tax complexity. Dividends are taxable income in the year they are received, and the marginal tax rate on Canadian eligible dividends can reach 39–46% depending on province and income level. The strategy works when the household has cash flow to cover the tax bill without touching the reinvested capital. It fails when the tax liability forces premature liquidation.
Smith Snider: Retirement De-accumulation
The "Smith Snider" flips the strategy for retirees. Instead of building a leveraged portfolio, it draws income from an existing one without triggering large capital gains spikes. A retiree with a $1.1 million taxable portfolio can borrow against home equity to fund living expenses, leaving the portfolio intact to compound. The borrowed funds are used to earn income, so the interest remains deductible. Over time, the retiree liquidates portions of the portfolio gradually, smoothing the tax burden across multiple years rather than concentrating it.
This is a tax-efficient withdrawal strategy. The risk is rising interest rates making the borrowed funds more expensive than the portfolio's after-tax return. It works when rates are low and the portfolio generates steady dividends and distributions, not speculation.
Rempel Maximum and Triple Top-Up: The Aggressive Outliers
The "Rempel Maximum" borrows a large lump sum upfront using structured investment loans alongside home equity, maximizing market exposure from day one. The "Triple Top-Up" layers borrowed home equity, traditional investment loans, and systematic recycling of tax refunds and portfolio distributions into a continuous reinvestment engine. Both require dedicated financial planning, tax coordination, and the psychological capacity to hold leveraged positions through multi-year downturns.
These are advanced tools for investors who have already succeeded with simpler variations and who are pursuing marginal gains in tax efficiency. Most working professionals will never need them.
Risk, Ranked
The Plain Jane carries the least risk because it moves slowly and requires no lump-sum decisions. The Singleton Shuffle and Debt Miracle are low-risk if the entry conditions are clean. The Top-Up and Using Dividends increase risk by adding lump-sum exposure or tax complexity. The Rempel Maximum and Triple Top-Up are high-risk because they assume the investor can sustain maximum leverage without panic-selling during corrections. The Smith Snider sits apart: low market risk, high interest-rate risk.
Choose the variation that fits the household's actual cash flow, the investor's actual risk tolerance, and the timeline that matches when the money will be needed.
Sources
Read Next
What 27 Rising Stars Under 40 Reveal About Canada's Next Wealth Model
The Deficit Fell $11.6 Billion. Your Mortgage Rate Didn't Get the Memo.
Banks Call It a Transfer Fee, but It Works Like an Exit Penalty
Leveraged Insurance Ends When Regulators See the Downside, Whatever the Math Says