A Portfolio Built to Last Can Still Outlive the Client's Independence
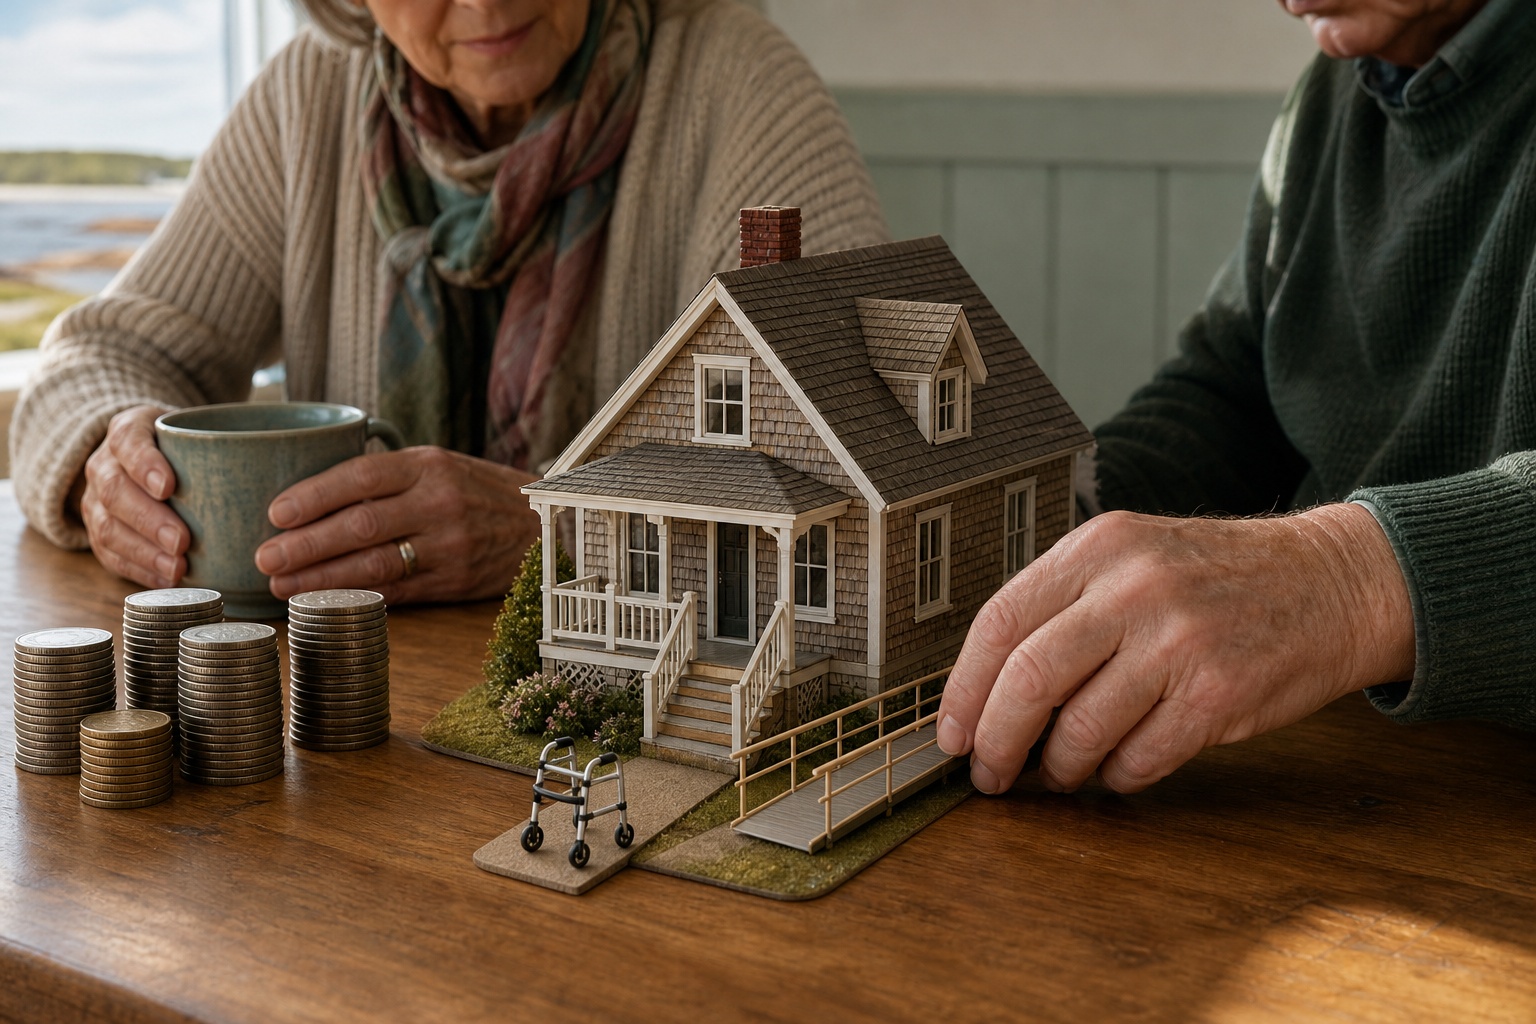
A retirement projection can show a client's money lasting into their late nineties and still say nothing about the year they stop driving, miss two property tax payments, or need help getting out of the bath. That gap usually surfaces during a fall, a diagnosis or a spouse's death, when the family has days to choose care, sell or adapt a house, and work out who is allowed to sign what. Five checks can reveal it while the client still has time and choices.
If you've ever finished a retirement review confident about the projections but uneasy about who would help the client manage bills or arrange care, you know the difference between a funded retirement and a workable one. The plan has to protect the client's ability to live and make decisions as well as their ability to keep paying. Run one existing plan through these questions before your next review.
Can the plan pay for the support the client may need?
1. Model changing support needs. Split everyday spending from the costs that tend to arrive later: home support hours, a ramp or main-floor bathroom, and eventually higher-support living. One smooth, inflation-adjusted spending line can make a plan look healthy while hiding a funding gap in the client's eighties. People skip this because the smooth line is easier to present, and nobody wants to open a review by talking about decline.
2. Identify which money could pay for care promptly. List what could be drawn within weeks and what each withdrawal would do to taxes and benefits. A large RRIF withdrawal adds to taxable income and can trigger OAS recovery, while TFSA withdrawals don't count as income. Confirm which public programs actually apply on the Island instead of assuming they'll fill the gap. Treat the house as a resource that needs a workable access plan, whether that's a sale, a smaller purchase or borrowing against it, each with its own timeline and trade-offs. Equity on a statement can take months to become money that pays a care bill.
3. Test whether staying at home is practical as well as affordable. Ask who shovels the driveway, who drives to appointments in Charlottetown, who calls when the furnace quits. Ask whether the son in Alberta is really the backup plan. Family help is often assumed by the client and never confirmed with the family.
Can the plan still work when the client needs help managing it?
A well-funded account helps no one if the client can't manage it and nobody else has the right to.
4. Separate who can help from who has legal authority. A trusted contact person on an investment account gives the firm someone to call if it has concerns about the client's wellbeing or possible financial exploitation. Being named gives that person no power to trade, withdraw funds or make decisions. Authority comes from a power of attorney for property, and health care decisions are covered by separate documents. Have the client see a PEI lawyer to put the right ones in place, and ask to see what exists. Advisors skip this because a completed trusted contact form feels like the job is done.
5. Agree on what brings the plan back for review. While the client is well, settle on triggers specific to them: a new support need, losing a caregiver, trouble keeping up with bills, a planned move. Write them down, along with their consent about whom you may contact. Age alone isn't a trigger, and turning 80 says nothing about capacity. Assessing capacity belongs to doctors and lawyers. Your role is noticing change and acting on what the client already agreed to, which lets you raise a concern without seeming to judge.
A retirement plan must protect the client's ability to live and make decisions, not just their ability to keep paying. Plans that do this give clients more choice before circumstances narrow it. At your next review, ask one question and write down the answer: "If you needed more help at home, what would have to change in this plan?"




A retirement projection can show a client's money lasting into their late nineties and still say nothing about the year they stop driving, miss two property tax payments, or need help getting out of the bath. That gap usually surfaces during a fall, a diagnosis or a spouse's death, when the family has days to choose care, sell or adapt a house, and work out who is allowed to sign what. Five checks can reveal it while the client still has time and choices.
If you've ever finished a retirement review confident about the projections but uneasy about who would help the client manage bills or arrange care, you know the difference between a funded retirement and a workable one. The plan has to protect the client's ability to live and make decisions as well as their ability to keep paying. Run one existing plan through these questions before your next review.
Can the plan pay for the support the client may need?
1. Model changing support needs. Split everyday spending from the costs that tend to arrive later: home support hours, a ramp or main-floor bathroom, and eventually higher-support living. One smooth, inflation-adjusted spending line can make a plan look healthy while hiding a funding gap in the client's eighties. People skip this because the smooth line is easier to present, and nobody wants to open a review by talking about decline.
2. Identify which money could pay for care promptly. List what could be drawn within weeks and what each withdrawal would do to taxes and benefits. A large RRIF withdrawal adds to taxable income and can trigger OAS recovery, while TFSA withdrawals don't count as income. Confirm which public programs actually apply on the Island instead of assuming they'll fill the gap. Treat the house as a resource that needs a workable access plan, whether that's a sale, a smaller purchase or borrowing against it, each with its own timeline and trade-offs. Equity on a statement can take months to become money that pays a care bill.
3. Test whether staying at home is practical as well as affordable. Ask who shovels the driveway, who drives to appointments in Charlottetown, who calls when the furnace quits. Ask whether the son in Alberta is really the backup plan. Family help is often assumed by the client and never confirmed with the family.
Can the plan still work when the client needs help managing it?
A well-funded account helps no one if the client can't manage it and nobody else has the right to.
4. Separate who can help from who has legal authority. A trusted contact person on an investment account gives the firm someone to call if it has concerns about the client's wellbeing or possible financial exploitation. Being named gives that person no power to trade, withdraw funds or make decisions. Authority comes from a power of attorney for property, and health care decisions are covered by separate documents. Have the client see a PEI lawyer to put the right ones in place, and ask to see what exists. Advisors skip this because a completed trusted contact form feels like the job is done.
5. Agree on what brings the plan back for review. While the client is well, settle on triggers specific to them: a new support need, losing a caregiver, trouble keeping up with bills, a planned move. Write them down, along with their consent about whom you may contact. Age alone isn't a trigger, and turning 80 says nothing about capacity. Assessing capacity belongs to doctors and lawyers. Your role is noticing change and acting on what the client already agreed to, which lets you raise a concern without seeming to judge.
A retirement plan must protect the client's ability to live and make decisions, not just their ability to keep paying. Plans that do this give clients more choice before circumstances narrow it. At your next review, ask one question and write down the answer: "If you needed more help at home, what would have to change in this plan?"
Read Next
What 27 Rising Stars Under 40 Reveal About Canada's Next Wealth Model
The Deficit Fell $11.6 Billion. Your Mortgage Rate Didn't Get the Memo.
Banks Call It a Transfer Fee, but It Works Like an Exit Penalty
Leveraged Insurance Ends When Regulators See the Downside, Whatever the Math Says